5 Hacks to Turn Everyday Spending into $1,000+ in Cash Back Rewards
5 Hacks to Turn Everyday Spending into $1,000+ in Cash Back Rewards
Learn how a multi-card approach can affect annual cash back, depending on your spending and repayment habits.
Written by
David Kindness
David Kindness is a finance, insurance and tax expert at BestMoney.com. He has written for Investopedia, The Balance, and Techopedia, sharing his deep expertise in taxation, accounting, and finance. A CPA with a Bachelor’s in Accounting, David has worked as a tax specialist and Senior Accountant for high-net-worth clients and businesses in the San Diego area.
The average U.S. household spent $78,535 in 2024—about $6,545 a month—on everything from groceries and gas to utilities and housing, according to theU.S. Bureau of Labor Statistics.
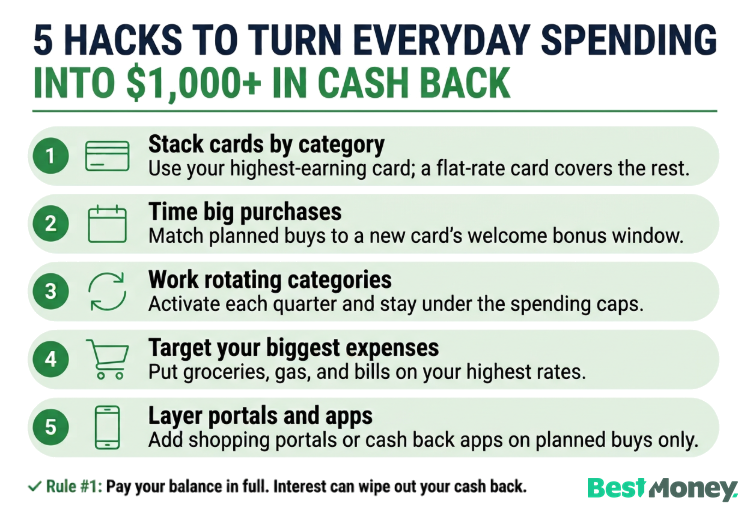
These 5 hacks to turn everyday spending into $1,000+ in cash back rewards focus on card fit and timing—not on spending more than you already planned. Start bycomparing cash back cards against your grocery, gas, and bill patterns.
With that much money moving through a household each year, even modest rebate rates can add up. And everyday earning is what cardholders care about most: in BestMoney's2026 Credit Cards Travel Survey of 1,000 U.S. adults, 47% of travel cardholders said earning points or miles on everyday purchases was the benefit they valued most—far ahead of welcome bonuses (7.3%).
Using one card for every purchase usually earns less than a category-based approach. The gap between roughly $200 and $1,000+ a year typically comes down to strategy: a flat-rate card, category or rotating cards, carefully timed welcome bonuses, and portals or apps only on planned buys.
Key Insights
Pay balances in full—interest can wipe out cash back fast.
Pair a flat-rate everyday card with category or rotating cards.
Time big purchases you already planned with welcome bonuses.
Activate rotating categories and stay under quarterly caps.
Put your biggest spending categories on your highest eligible rates, and stack portals and cash back apps only on planned buys.
What Is Cash Back, and How Do You Earn It?
Cash back is a purchase rebate you redeem later—usually as a statement credit or deposit—not an instant discount at the register.
Issuers track eligible spending after a purchase posts. You earn a percentage back when the purchase codes into an eligible category, and the rate depends on how the card is designed. Exact percentages vary by issuer and change over time. For a fuller primer on points, miles, and cash back, see our guide tohow credit card rewards work.
Card type
How it typically works
Best used for
Flat-rate
Same percentage on nearly all purchases
Catch-all everyday spending
Fixed-category
Higher rates on set buckets such as groceries or gas
Your largest recurring categories
Rotating-category
Elevated rates that change by quarter, often with a cap
Seasonal or planned category bursts
Choose-your-category
Higher rate in a category you pick from the issuer's list, often with a cap
Spending that shifts between categories
One rule underpins every hack here: pay the balance in full. Interest on a carried balance can quickly outweigh a 1%–6% rebate. The Consumer Financial Protection Bureau has also flagged rewards-program pitfalls such as surprise promotional conditions, devalued rewards, and redemption problems (CFPB credit card rewards issue spotlight), so read the terms before you build a strategy around any card.
Who Is This Cash Back Guide For?
This guide is for readers who want more cash back on everyday spending without treating card chasing like a second job.
Everyday spenders who pay in full: You cover groceries, gas, utilities, and shopping and want a higher effective rebate.
People open to about 2–4 cards: You'll match categories, not juggle a dozen due dates.
Shoppers comparing options first: You research cash back rewards structures before you apply.
Not ideal if you carry high-APR balances: Artificial spending or revolving debt to "earn" rewards usually costs more than the rebate.
Hack 1: How Do You Stack Cash Back Cards for Everyday Spending?
You stack cards by putting each purchase on the highest eligible rate, then sending leftover spending to a strong flat-rate card.
Think of it like choosing the right tool for each household job: one catch-all card for odd purchases, and specialists for the big recurring categories. Using one card for every purchase is a common rewards mistake; multiple cards can earn more when categories and terms line up.
How Do You Build a Practical Card Combination?
A practical setup pairs one catch-all flat-rate card with cards that boost your largest categories—and, when it fits, a way to earn rewards on housing payments.
Everyday card: Use a flat-rate card for purchases that don't earn more elsewhere.
Rotating-categories card: Use elevated quarterly categories when you activate them, and stay under the caps.
Grocery or gas specialist: Use a fixed-category card when those buckets dominate your budget. Confirm live rates and annual caps with the issuer.
Housing payments: Some programs let you pay rent or mortgage through a rewards platform with no transaction fee. Confirm current terms before you rely on any rate.
For most people, pairing a flat-rate "everything else" card with one or two boosted-category cards is enough. For a deeper look at running several cards at once, see our guide tousing multiple cash back cards.
How Much Could Category Stacking Add on $4,000 a Month?
This illustrative model shows how category matching can change annual totals versus a single 1% card. It's a worksheet example, not a promise—your categories, caps, and bonus rates will differ.
Category (example monthly spend)
Boosted rate example
Boosted monthly rewards
1% basic card
Groceries ($800)
6%
$48
$8
Gas ($300)
3%
$9
$3
Rotating category ($500)
5%
$25
$5
Everything else ($2,400)
2%
$48
$24
Total ($4,000)
—
$130
$40
In this model, boosted rewards total about $130 a month versus $40 on a 1% card—roughly $1,560 versus $480 a year before fees. Watch the caps, though: 6% grocery rates often apply only to the first $6,000 in supermarket purchases a year, then drop to 1%. At $800 a month, you'd hit that cap in August, which trims the annual total to about $1,380—still well past $1,000. Some high-rate grocery cards also charge an annual fee, so subtract it. Match your highest spending categories first, and let the flat-rate card clean up the rest.
Hack 2: How Do You Time Large Purchases for More Cash Back?
You time large purchases by lining up planned spending with a welcome-bonus window on a card you'd keep using—only for buys you'd make anyway.
Welcome bonuses can meaningfully increase total rewards, depending on spending requirements, fees, and card fit. Yet many people don't line up applications with major purchases they've already budgeted.
How Should You Plan Applications Around Big Purchases?
Plan the purchase first, then the application, so real bills meet the spending requirement.
Plan large purchases 3–4 months ahead.
Apply 1–2 weeks before a major purchase (after confirming the merchant accepts cards).
Verify the live welcome offer before you apply—thresholds change often.
When Are Useful Times to Apply for a New Cash Back Card?
The best windows are seasons with large, unavoidable bills.
Home improvements: Apply before contractor payments if the contractor accepts credit cards.
Holiday shopping: Time applications for October–November spending you've already budgeted.
Back-to-school: Apply in July for August–September purchases you'd make anyway.
Business or quarterly payments: Use legitimate business expenses already on your calendar when they help meet a spending threshold.
Example: A $3,500 home project paid on a 1% card earns about $35. On theBank of America® Customized Cash Rewards card, you could set your choice category to home improvement and furnishings, which includes hardware stores, furniture stores, and contractors such as plumbers, electricians, and carpenters. In the first year, the first $2,500 earns 6% ($150) and the remaining $1,000 earns 1% ($10), for $160. The same spending also meets the card's $200 cash rewards bonus offer welcome bonus requirement of $1,000 in purchases within the first 90 days—about $360 in total instead of $35.
If your payments fall in two different calendar quarters, such as a deposit and a final payment, more of the spending can earn 6%. Grocery and wholesale club purchases share the same $2,500 quarterly cap, so count them too. Merchants set their own category codes, and standalone appliance stores may not code as home improvement, so check before a big purchase. Treat dollar examples as illustrations only.
Pro tip: Keep spending inside the introductory offer window so purchases count toward the bonus.
Hack 3: How Do You Maximize Rotating Category Cash Back?
You maximize rotating categories by activating each quarter, planning eligible spending inside the window, and respecting caps and how merchants code purchases.
Rotating cards raise rates on different categories each quarter. Earning the full benefit takes planning—not last-minute swipes. Confirm the live calendar in your issuer's app.
How Do Quarterly Categories Usually Work?
Quarterly lineups change by issuer and year. Treat the pattern below as an example, not a live schedule.
Q1 (January–March): Often includes gas, groceries, or drugstores.
Q2 (April–June): Frequently features home improvement, major online retailers, or wholesale clubs.
Q3 (July–September): Typically includes restaurants, entertainment, or digital wallets.
Q4 (October–December): Usually covers department stores, warehouse clubs, or online shopping.
Some cards let you choose your own categories instead. The U.S. Bank Cash+® Visa Signature® Card, for example, lets you pick two 5% categories each quarter (on the first $2,000 in combined purchases) plus one 2% everyday category. That flexibility helps when a fixed rotating list doesn't match your spending.
The Bank of America® Customized Cash Rewards card takes a monthly approach: you pick one category from gas and EV charging, online shopping, dining, travel, drug stores, or home improvement and furnishings, and you can change it once each calendar month. Earn 6% cash back for the first year in the category of your choice. You’ll automatically earn 2% cash back at grocery stores and wholesale clubs, and unlimited 1% cash back on all other purchases. After the first year from account opening, you’ll earn 3% cash back on purchases in your choice category. Earn 6% and 2% cash back on the first $2,500 in combined purchases each quarter in the choice category, and at grocery stores and wholesale clubs, then earn unlimited 1% thereafter. After the 3% first-year bonus offer ends, you will earn 3% and 2% cash back on these purchases up to the quarterly maximum.
What Tactics Help You Earn More in Bonus Categories?
A few habits stretch a short bonus window without forcing extra spending.
Category stacking: Combine rotating-card spending with other eligible rewards when terms allow.
Gift cards (with caveats): They may extend value later, but issuers often restrict or exclude them.
Quarterly acceleration: Concentrate eligible purchases you'd make anyway during bonus periods.
How Can Gift Cards Fit—Without Backfiring?
If a major retailer is a bonus category, some people buy gift cards there for later use. That only works if the purchase codes correctly and isn't excluded. Category bonuses usually depend on where you pay—not on every item in the cart. Make a small test purchase before you load large amounts.
Hack 4: How Do You Optimize Your Biggest Spending Categories?
Put your highest annual spending on the highest eligible rate. Then check housing and business payments for program-approved payment methods—not outside services that charge fees.
Many people chase rewards on small purchases while missing their largest expense categories. See our guide tomaximizing credit card rewards for broader tactics.
Which Everyday Categories Usually Move the Needle?
Start with your last 90 days of statements. The dollar amounts below are illustrative scenarios for rate math—not official averages for every household.
Category (illustrative annual spend)
Example higher rate
Example vs. 1% card
Groceries (~$6,000)
6%
About $300 more than 1%
Gas (~$2,400)
3%
About $48 more than 1%
Utilities (~$3,000)
2% catch-all
About $30 more than 1%
Streaming/subscriptions (~$600)
Higher rate on some cards
Depends on coding and caps
Groceries are a good place to start. The average household spent $6,224 on food at home in 2024, per BLS data, so routing about $6,000 through a 6% grocery rate instead of 1% can mean roughly $300 a year before any portal or app layer. Gas and utilities matter too, but groceries often dominate family budgets. Before you plan around utilities, check whether your provider charges a card-payment fee.
How Can Business Expenses Help—Responsibly?
If you have legitimatecharges on a business credit card, look for elevated rates on office supplies, internet, phone, and advertising. Use those rates only for real business spending you can pay in full.
How Do Rent and Mortgage Rewards Work Now?
Many landlords don't accept credit cards directly. Housing-focused rewards programs can let members pay rent or mortgage through the platform with no transaction fee on eligible payments, then earn points or program currency depending on how housing rewards are unlocked.
Bilt is one example. Under its Bilt Card 2.0 lineup, cardholders earn Bilt Cash on everyday spending and can use it to unlock points on rent and mortgage payments—different from the older "simple points on rent" setup. Don't assume a flat cash back rate on rent. Be cautious with third-party bill-pay services that charge percentage fees; they only make sense if net rewards after fees still beat paying another way. Verify current program terms before you build a strategy around housing rewards.
Hack 5: How Do You Stack Portals and Cash Back Apps?
Start in an eligible portal or app, then pay with the card that earns the most at that merchant—only when the combined effective rate beats the fees and friction.
How Do Shopping Portals and Apps Add Another Layer?
Portals and apps pay their own rebate when you begin the purchase through them.
Issuer portals: Elevated rates at select retailers, plus your card's base rate when stacking is allowed.
Independent portals: Percentage cash back at many stores, often stackable with card rewards (Rakuten is one example).
Cash back apps: Extra offers on groceries and retail when you follow offer rules (examples include Ibotta and Checkout 51).
Triple-stacking method (illustrative): Start in a portal, pay with a rotating-category card when the merchant qualifies, and add an app offer if one applies. Live rates change constantly—treat this as a method, not a locked percentage.
Which Issuer Portal Tools Are Worth Checking?
If you already hold cards from these issuers, their portals and offer hubs are worth a look:
Shop through Chase: Extra points or cash back at partner retailers through the Chase Ultimate Rewards® portal.
Amex Offers: Targeted deals that pay statement credits after you enroll.
Citi Shop and Citi Merchant Offers: Cash back at participating merchants when offers are active.
Combined rewards often peak during major shopping events. Stack only when you'd buy the item anyway.
What Mistakes Can Wipe Out Your Cash Back Rewards?
Interest, fees, late payments, and overspending can erase cash back even when category rates look strong.
Interest charges: Pay the balance in full every month—it's the first of ourcredit card tips for a reason. Revolving debt can cancel out rebates quickly.
Annual fee miscalculation: Premium cards need enough extra rewards to clear the fee. Compare rewards earned versus fees paid each year.
Overcomplicating your system: Too many cards can backfire. Manage only what you can track.
Missing due dates:Late payments add fees and can trigger penalty APRs.
Spending creep: Track monthly totals so rewards chasing doesn't raise your expenses. Only charge what you'd spend anyway.
What Advanced Tactics Can Serious Cash Back Earners Use?
For readers comfortable managing multiple cards, these techniques may boost annual rewards depending on spending, fees, and eligibility.
Business cards:Business credit cards may offer higher category limits on real business spending paid in full.
Skip artificial spending: Don't create fake purchases just to hit bonuses. Stick to planned expenses.
Measured new accounts: Welcome bonuses can help, but new applications requirebuilding credit responsibly and can affect your score in the short term.
Put cash back to work: Some people apply redeemed cash back to expenses while saving income elsewhere. That's budgeting, not an investment promise.
How Do You Build a Personal Cash Back Strategy?
Audit real spending, match cards to those categories, add products slowly, and review results each quarter.
Monthly spending audit: Track three months of expenses and totals by category.
Implementation timeline: Start with one or two cards. Add others only when due dates stay manageable.
Quarterly reviews: Compare rewards earned versus fees paid, and adjust.
Your Questions, Answered (FAQs)
How many credit cards should I have to earn more cash back?
A manageable setup for many readers is 3–4 rewards cards: one everyday card, one rotating-category card, and one or two category specialists such as groceries or gas. If you're worried about going overboard, seecan you have too many credit cards.
Can I really earn $1,000+ a year in cash back rewards?
Yes, with enough monthly spending and a multi-card plan that matches categories and times large purchases with welcome bonuses. At lower spending levels you'll still benefit, but totals scale with the eligible purchases you pay in full.
Are annual fees worth it for cash back cards?
Only if the extra rewards exceed the fee after accounting for caps and the categories you actually use. Compare a fee card against a no-fee alternative using your real spending.
What are the main downsides of chasing cash back?
Interest, annual fees, late fees, and overspending can erase rewards if you don't pay in full or you buy things just to earn a rebate. Cash back works best when the purchase was already in your budget.
Is credit card cash back taxable?
Cash back earned on purchases is generally treated as a rebate that reduces the purchase price, not as taxable income. Rewards that don't require spending—such as some referral or account-opening bonuses—can be treated differently. This isn't tax advice; confirm edge cases with a tax professional.
What's the Bottom Line on Earning More Cash Back?
Turning everyday spending into $1,000+ in annual cash back rewards is about card fit, timing, selective portals, and payoff discipline—not spending more.
Use these five hacks as a simple system: stack categories, time bonuses, respect rotating calendars, protect your biggest expense buckets, and add portals only when the math still works after fees.
What Should You Do Next to Earn More Cash Back?
Here's a simple three-step plan to get started:
Audit 90 days of spending. List groceries, gas, dining, online retail, and housing.
Shortlist cards that fit those categories.Compare cash back cards side by side, and apply only if the fee and category math fit your budget.
Layer peak-season tactics when budgets spike. For holiday spending, use the same stacking rules and see our picks forearning rewards on holiday purchases.
Why Trust BestMoney?
This article is written byDavid Kindness, a CPA and finance, insurance, and tax expert at BestMoney.com who has worked as a tax specialist and senior accountant and has covered taxation and personal finance for Investopedia, The Balance, and Techopedia.
For this refresh, we checked household spending figures against the latest BLS Consumer Expenditure Survey data, verified card terms against issuers' own pages, reviewed CFPB research on rewards programs, and drew on BestMoney's own survey of 1,000 U.S. adults. Illustrative math is labeled as a model.
How We Researched This
This refresh combines BestMoney's 2026 Credit Cards Travel Survey (1,000 U.S. adults) with secondary sources: BLS spending data from the December 2025 Consumer Expenditure Survey release, CFPB research on credit card rewards, issuer terms for the specific cards named, and housing-rewards program documentation for current rent and mortgage rules.
Illustrative reward math uses example rates and spending levels labeled as models, not guaranteed outcomes. Card offers and portal rates change—confirm terms with the issuer.
BestMoney may receive compensation from some of the card issuers featured on this page, including Bank of America. This may influence which products we cover and where they appear, but it does not affect our editorial evaluations. Not all card offers available in the market are included. Card details are accurate as of publishing date and are subject to change. Your APR will depend on your creditworthiness. Terms and conditions apply. See the issuer’s website for current rates, fees, and full terms. All cards are subject to credit approval. Prequalification is not a guarantee of approval. Checking prequalification uses a soft inquiry that won’t affect your credit score; submitting a full application results in a hard inquiry. Examples are for illustration only and are rounded. They assume no additional purchases, on-time payments, and no other fees. Your actual costs will depend on your APR, balance, and payment behavior.
Written byDavid Kindness
David Kindness is a finance, insurance and tax expert at BestMoney.com. He has written for Investopedia, The Balance, and Techopedia, sharing his deep expertise in taxation, accounting, and finance. A CPA with a Bachelor’s in Accounting, David has worked as a tax specialist and Senior Accountant for high-net-worth clients and businesses in the San Diego area.