What Charges Can You Put on a Business Credit Card?
What Charges Can You Put on a Business Credit Card?
Most business costs can go on the card, but taxes treat them differently. Here's what to charge and what to skip
Written by
Meagan Drew
Meagan Drew is a personal finance and loans expert at BestMoney.com. She has written for publications such as Investopedia, Apple News+, and SimpleMoneylyfe.com. With seven years of experience as a financial advisor, Meagan specializes in making complex topics like budgeting and investing accessible and engaging for everyday consumers.
Common business credit card expenses you can charge, plus restrictions and smart habits to follow. In theFederal Reserve's 2026 Report on Employer Firms, 62% of small employer firms surveyed said they regularly use credit cards. The survey covered firms with 1–499 employees.
Business credit cards allow you to manage your company expenses whileearning rewards and keeping your personal and business finances separate. They're built for a wide mix of business costs, whether you're buying office supplies, booking travel, purchasing inventory, or launching marketing campaigns.
So, what charges can you put on a business credit card? Understanding which purchases make sense helps you get more value while avoiding issues with your card issuer, the tax authorities, or business partners. It also helps whencomparing credit cards side by side, since rewards should match where your money goes.
This guide walks you through the purchases you can make and offers practical advice for using your card wisely. It reflects IRS guidance as of September 2026. That includes 2026 mileage rates and the meal and entertainment rules in the 2025 edition of IRS Publication 463.
Key Insights
You can generally charge any ordinary and necessary business expense the vendor accepts by card.
Keep personal and business spending separate to simplify tax time and avoid accounting headaches.
Business meals are generally 50% deductible, but entertainment isn't deductible, per the IRS.
Cash advances and cash-like purchases usually start accruing interest right away.
62% of small employer firms regularly use credit cards, per the Federal Reserve's 2026 report.
Choose a card that rewards the categories where your business spends the most.
Keep receipts and note the business purpose of each charge, per IRS Publication 463.
What Charges Can You Put on a Business Credit Card?
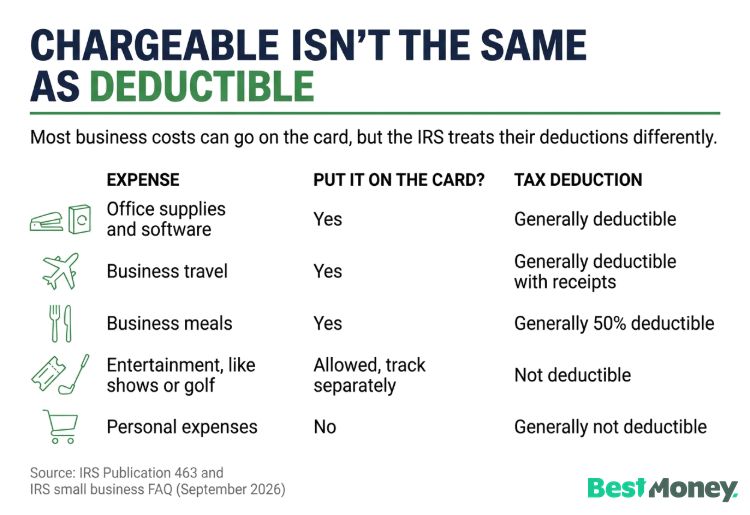
You can generally charge any business expense a vendor accepts by card. Whether that charge is tax-deductible is a separate question.
For deductions,IRS Publication 463 uses an "ordinary and necessary" test. An ordinary expense is common and accepted in your trade, and a necessary one is helpful and appropriate for your business. The same publication says business meals are generally 50% deductible, while entertainment isn't deductible.
Think of the test as a receipt checklist. Before you swipe, ask whether the cost is normal for a business like yours and whether it helps the business run. If both answers are yes, it likely belongs on the business card.
Common Business Card Charges at a Glance
Expense
Good fit for a business card?
Tax note
Office supplies and equipment
Yes
Generally deductible if ordinary and necessary
Software subscriptions
Yes
Generally deductible if ordinary and necessary
Business travel
Yes
Generally deductible with receipts
Client or business meals
Yes
Generally 50% deductible
Entertainment, such as shows or golf
Allowed, but track it separately
Not deductible
Inventory
Yes
Business cost; ask your accountant how to record it
Advertising
Yes
Generally deductible if ordinary and necessary
Federal taxes
Yes, through IRS-approved processors
Processor fee applies; the fee is deductible for businesses
Personal expenses
No
Generally not deductible
What Everyday Business Expenses Can You Charge?
Your business credit card can cover the regular costs of running your company:
Office supplies and equipment: Paper, pens, printers, and furniture fit well on cards with category rewards at office supply stores.
Utility bills: Put your business electricity, water, internet, and phone bills on your card to create a clear payment record and potentially earn rewards.
Software subscriptions: Business software, cloud storage, productivity apps, and specialized applications are common card charges that are easy to track for tax purposes.
Communication expenses: Use your card for mobile phone plans, video conferencing services, and other services for staying connected with clients and team members.
Technology purchases: Computers, tablets, point-of-sale systems, and other tech can go on your card. Some premium cards add extended warranty protection.
Office maintenance costs: Your card can manage cleaning services, repairs, maintenance contracts, and general upkeep expenses.
Can You Charge Business Travel and Meals?
Yes, but IRS Publication 463 treats business meals and entertainment differently, so track them separately. Travel and client entertainment are large expenses for many businesses, and business cards can add benefits here:
Flights and transportation: Charge airfare, train tickets, and car rentals.Travel-focused credit cards may add bonus points and protections like trip cancellation insurance.
Accommodation expenses: Hotel stays, conference room rentals, and lodging for business trips are common business card charges that might earn extra rewards points.
Meals and client entertainment: Business meals are generally 50% deductible when you or an employee attends. Entertainment, like shows or golf, isn't deductible.
Ride-sharing and transportation services: Local transportation on business trips, including taxis, Uber, Lyft, and public transit, makes sense to put on your business card.
Travel-related incidentals: Use your card for baggage fees, in-flight purchases, hotel Wi-Fi, and other extras to track total trip costs.
Employee travel expenses: Company or employee cards with spending limits can manage staff travel costs and centralize expense tracking.
Yes, your business credit card can handle many operating expenses that are central to your business:
Raw materials: Materials for manufacturing or production can go on your card, bridging the gap between buying materials and selling products.
Product inventory: Use your card for wholesale products, resale inventory, and merchandise. These larger purchases can add up to more rewards.
Packaging supplies: Boxes, mailers, labels, and packaging materials are legitimate business expenses that are easy to track through your card statements.
Shipping costs: Put postage, courier services, freight charges, and delivery expenses on your card to keep these costs in one place.
Manufacturing equipment: Smaller equipment and machinery parts work well as card charges. For large capital investments, weigh abusiness credit card vs. business loan.
Wholesale purchases: Bulk orders from suppliers and wholesale vendors suit a business card and can earn more rewards if you spend heavily here.
Pro tip: Operating purchases are often your largest expense categories, so weigh them carefully when choosing a card. Our guide onhow to maximize your credit card rewards explains how to match rewards to your spending.
Can You Charge Marketing and Growth Expenses?
Yes, marketing and outreach costs are common business card charges. Here's how your card can add flexibility:
Digital marketing campaigns: Use your card for Google Ads, social media advertising, and email marketing services.
Social media promotion: This includes boosted posts, platform-specific advertising, and social media management apps for easy tracking.
Print marketing materials: Business cards, brochures, flyers, signage, and other physical marketing items are common business card expenses.
Graphic design services: Professional design work, logo creation, and branding services fall under legitimate business spending.
Website development: Use your card for domain registration, hosting services, website design, and maintenance.
Content creation tools: Software, equipment, and services needed to create content for your business are valid card expenses.
Pro tip: Marketing costs often rise and fall with the seasons or your growth plans. A card's flexibility can help you manage cash flow while you expand.
Can You Pay Taxes, Gas, or Professional Services With a Business Card?
Yes, all three can go on a business card, with a few limits. The table below shows what to know as of September 2026.
Fees run about 1.75% to 2.95%, depending on processor and card type, with higher rates listed for commercial cards. Fees are deductible for businesses.
Federal tax deposits, such as payroll taxes
No
The IRS doesn't accept card payments for federal tax deposits.
Commuting isn't deductible, per IRS Publication 463.
Professional services and insurance
Yes, if the provider accepts cards
Legal, accounting, and business insurance costs are common business charges.
For gas deductions, IRS Publication 463 says you choose the standard mileage rate or actual car expenses, such as gas, for a given year. If you also drive the car personally, split costs by business and personal miles.
Can You Use a Business Credit Card for Personal Expenses?
You technically can in some cases, but it's risky, and personal charges generally aren't tax-deductible. TheIRS small business income and expenses FAQ says personal, living, or family expenses are generally not deductible. It also suggests keeping separate business and personal accounts.
Mixing is common, though. In the same Federal Reserve report, 34% of employer firms that regularly use credit cards use both personal and business cards.
Practical realities of sole proprietorship: Fully separating business and personal costs can be hard. Keeping them apart where possible makes accounting clearer.
Risks of mixing charges: Mixing risks tax and card-agreement problems. TheSBA's banking guide says keeping business funds separate offers limited personal liability protection.
Issuer views on personal spending: Card agreements vary, and some issuers may overlook an occasional personal charge, but heavy personal spending could violate them.
Business cards also come with fewer legal protections. TheCFPB's official Regulation Z commentary says business-purpose cards are generally exempt from most consumer credit card rules under Regulation Z. The CARD Act applies only to consumer credit cards, not small business cards, according to a2013 CFPB report on the CARD Act.
Rules on card issuance and unauthorized-use liability still apply to business cards.
Most business cards require a personal guarantee,according to Chase. A personal guarantee is your promise to repay the debt yourself if the business can't. It works a lot like co-signing a loan for your company.
Corporate cards typically don't hold individual cardmembers liable in the same way. Learnwhat a corporate credit card is and how it differs.
Pro tip: A cleaner approach is keeping separate cards for business and personal use. When an occasional crossover happens, clear documentation and proper accounting allocations become essential.
What If You Accidentally Charge a Personal Expense?
Fix it quickly by repaying the business and documenting what happened:
Repay the business from your personal funds.
Record the charge in your books, such as an owner's draw, based on your accountant's advice.
Keep a short note with the date, amount, and reason.
Leave the charge out of your business deductions.
Ask your accountant if you're unsure how to categorize it.
What Charges Should You Avoid on a Business Credit Card?
Avoid personal costs, cash advances, cash-like purchases, and large purchases you can't repay quickly. Be cautious with these charges:
Large capital purchases: Major equipment, real estate, or vehicle purchases might exceed your limit or prompt an issuer review, depending on your card agreement.
Personal luxury items: High-end personal purchases unrelated to your business may raise red flags with card issuers and tax authorities.
Charges with no clear business purpose: These create accounting complications and potential tax issues.
Cash advances and cash-like purchases: Interest on acash advance starts right away, unlike purchases, and fees usually apply.
Potential red flags for card issuers: Unusual spending, restricted merchant categories, or signs of financial trouble could prompt an issuer review, depending on your agreement.
A cash advance is borrowing cash against your card's credit line, often at a higher rate than purchases. Some cash-like purchases count, too.
For example, theAmerican Express Amazon Business Card agreement lists money orders, foreign currency, and casino gaming chips as cash advances. Other issuers set their own lists, so check your cardmember agreement.
How Can You Get More Value From Business Card Charges?
You get more value by matching your card to your spending, tracking each charge, and using the perks you already have. Here's how:
Understand reward structures: Choose cards with rewards that match your highest spending categories, whether that's office supplies, travel, or general purchases.
Flat-rate cash back: If your expenses vary,cash back cards with one flat rate keep rewards simple.
A recent flat-rate example: U.S. Bank's two new business cards offer unlimited 2% cash back on eligible purchases, per aSeptember 2026 press release.
Category-bonus alternative: Other cards pay more in set categories, such as office supplies or travel. See howcash back categories work.
Travel rewards strategies: If your business involves frequent travel, you might benefit more from cards offering transferable points, hotel status, or airline-specific benefits.
Tracking and categorizing expenses: Use issuer features, accounting software, or expense platforms to sort spending automatically for easier tax prep.
Employee cards and expense policies: Set spending limits and a written policy for employee cards. See our guide tobusiness credit card expense tracking.
Leveraging card-specific perks: Perks may include extended warranties, purchase protection, rental car coverage, orairport lounge access. Check what yours includes.
By matching spending to the right card rewards and managing your accounts actively, you can turn necessary business expenses into benefits for your company.
Who Is This Guide For?
This guide is for U.S. small business owners, freelancers, and sole proprietors deciding what belongs on a business card. Start with the section that fits you:
If you own an LLC or corporation: IRSPublication 583 advises keeping business and personal accounts separate, so give your company its own card.
If you have employees: Prioritize a written expense policy and employee cards with spending limits.
If you travel often: Review the travel and meals rules, since meals and entertainment get different tax treatment.
If you sell physical products: Watch inventory spending closely. With a 0% intro APR card, plan to repay before the promo period ends.
What's the Bottom Line on Business Credit Card Charges?
Business credit cards give you flexibility to manage most legitimate business expenses while offering rewards and organizational benefits. Charge ordinary and necessary costs, keep personal spending separate, document each purchase, and steer clear of cash-like charges.
Review your spending categories regularly, make sure you're using the right card for each purchase type, and check with an accountant about your business structure.
Your Questions, Answered (FAQs)
Can I pay for gas with my business card?
Yes, for business driving. For deductions, the IRS lets you use the standard mileage rate or actual expenses like gas in a given year, not both.
Can I use a business credit card for food?
Yes, for business meals, which the IRS generally treats as 50% deductible when you or an employee is present and the meal isn't lavish. Personal groceries and family meals don't belong on the card.
Can I pay my business taxes with a credit card?
Yes, you can pay federal taxes through IRS-approved processors. Fees run about 1.75% to 2.95% as of September 2026, with higher rates listed for commercial cards. Federal tax deposits, such as payroll taxes, can't be paid by card.
Does a business credit card affect my personal credit?
It can, because most business cards require a personal guarantee that ties you to the debt. Credit reporting varies by issuer, so check your card's terms.
What are the downsides of a business credit card?
You'll usually sign a personal guarantee, and business cards fall outside most consumer card rules under Regulation Z. Some cards also charge annual fees, so weigh costs against rewards.
Why Trust BestMoney?
This guide comes fromMeagan Drew, a personal finance and loans expert at BestMoney.com. According to her BestMoney author profile, she has written for publications such as Investopedia, Apple News+, and SimpleMoneylyfe.com.
With seven years of experience as a financial advisor, Meagan specializes in making complex topics like budgeting and investing accessible and engaging for everyday consumers.
How We Researched This
This article relies on secondary research, not a BestMoney survey or proprietary dataset. BestMoney's editorial team reviewed IRS guidance on business expenses, tax payments by card, and 2026 mileage rates.
We also reviewed CFPB rules and cash advance guidance, the Federal Reserve's 2026 Report on Employer Firms, and issuer documents and press releases. We checked each tax and fee figure against its primary source in October 2026.
Where We Got Our Information
Internal Revenue Service, Publication 463: Travel, Gift, and Car Expenses (2025 edition, reviewed April 30, 2026)
Internal Revenue Service, Pay Taxes by Card or Digital Wallet (reviewed September 24, 2026)
Internal Revenue Service, Standard Mileage Rates (updated July 28, 2026)
Internal Revenue Service, Small Business and Self-Employed Income and Expenses FAQ (accessed October 2026)
Consumer Financial Protection Bureau, Official Interpretation of Regulation Z Section 1026.3 (accessed October 2026)
Consumer Financial Protection Bureau, Can I Withdraw Money From My Credit Card at an ATM? (reviewed September 2, 2026)
Federal Reserve Banks, Small Business Credit Survey: 2026 Report on Employer Firms (March 3, 2026)
Chase, What Happens If I Can't Pay My Business Credit Card? (accessed October 2026)
American Express, Amazon Business Card Cardmember Agreement (October 8, 2025)
U.S. Bank, Press Release on New Small Business Credit Cards (September 28, 2026)
Internal Revenue Service, Publication 583: Starting a Business and Keeping Records (Rev. December 2024)
U.S. Small Business Administration, Open a Business Bank Account (December 2025)
Meagan Drew is a personal finance and loans expert at BestMoney.com. She has written for publications such as Investopedia, Apple News+, and SimpleMoneylyfe.com. With seven years of experience as a financial advisor, Meagan specializes in making complex topics like budgeting and investing accessible and engaging for everyday consumers.