Last updated: Sep 2026
Our Best Auto Loan Services September 2026
Find rates. Discover freedom.

A car loan is a financing agreement where a lender provides funds specifically for purchasing a vehicle, and the borrower repays the loan over time with interest. Car loans are increasingly common because vehicles have become essential for daily use, such as commuting, transporting family, or accessing work opportunities.
Vehicle-specific financing means the car (or motorcycle) serves as collateral.
Financing allows borrowers to acquire mobility even if they don’t have full cash on hand.
Understanding how a car loan works helps you make informed decisions and avoid costly mistakes.
LendingTree is a marketplace where you can set your parameters and then receive a list of relevant loan providers. One of the perks of LendingTree is that you fill out one application and can then review multiple loan options.
Pros | Cons |
Vast network of loan providers may help you find competitive rates | Work with all types of credit |
Not directly a lender, so rates and terms vary | Lack of information about specific loan types and terms |
PenFed is a national credit union that offers auto loan rates for new and used vehicles. It also offers auto loan refinancing with rates that compete with national banks, plus a car buying service that includes discounted prices and rates.
Pros | Cons |
Car buying service with even more discounted rates | Must join PenFed credit union to receive a PenFed product |
Can borrow over the value of your vehicle | Rates vary based on credit score |
ConsumersCreditUnion’s online approval process means you can get your personalized down payment and monthly payment on every car before you start shopping. Their customers, on average, can save over $1,000 on their down payment for similar cars on sale elsewhere.
Pros | Cons |
Can be used for both new and used cars | Credit union membership required to receive a loan offer |
Provides 24/7 customer service on the phone | Higher rates for older cars |
Vehicles enable freedom of movement, allowing you to commute to work, transport children, visit relatives, and expand your income potential beyond the limitations of walking or public transit. Given that even budget vehicles often cost thousands of dollars, car loan providers offer affordability and flexibility by:
Allowing borrowers to spread the purchase cost over multiple payments.
Offering financing solutions even when cash liquidity is limited.
Helping consumers access reliable transportation through structured financing.
At BestMoney.com, we understand the importance of making informed financial decisions. Our team of financial experts and editors conducts thorough research across lending, banking, home loans, personal finance, and insurance to provide you with comprehensive comparisons and insights. We continuously update our content to reflect the latest market trends and offerings, ensuring you have access to current, reliable information.
We offer a wide range of services including detailed comparison tools and expert reviews, all designed to meet your specific financial needs. Our mission is to empower you to make confident, well-informed choices that help you achieve your financial goals.
Optimize your credit profile
Focus on total cost, not just the monthly payment
Treat dealer financing as a last resort
Shop multiple lenders within a short period
Use pre-approval as leverage
Two loans with the same monthly payment can differ by thousands over their lifetime. Dealers and lenders often compete on the payment figure because it's the number buyers react to, which hides differences in term length, rate, and fees. Comparing properly means holding the loan amount and term steady, then reading the total cost rather than the monthly one.
1. Compare APR, Not the Monthly Payment
Request every quote using the same loan amount and the same term, then compare APR, which includes fees the interest rate alone leaves out. A lower monthly payment stretched over a longer term almost always costs more in total, so a cheaper-looking payment is often the more expensive loan.
2. Get Quotes From More Than One Type of Lender
Banks, credit unions, online lenders, and dealerships price the same borrower differently, and credit unions in particular often undercut dealer financing. Treat dealer financing as one quote among several rather than the default, since it's the offer you're most likely to accept out of convenience rather than value.
3. Submit Your Applications Within a Short Window
Rate-shopping inquiries filed close together are generally treated as a single event by credit scoring models, typically within a 14-day window. Spreading applications over several weeks can cost you points on the score that determines your rate, so shop in one concentrated stretch.
4. Get Pre-Approved Before You Shop
A pre-approval gives you a real rate to negotiate against instead of relying on whatever the dealer's finance office offers. Confirm the pre-approval covers the full amount you'll need, since a quote that excludes taxes, registration, or add-ons won't hold up at signing.
5. Check the Total Cost of Ownership, Not Just the Loan
Insurance, maintenance, and fuel differ meaningfully by vehicle and belong in the comparison alongside the payment. A cheaper loan on a more expensive car to insure can leave you paying more each month than the loan comparison suggested.
6. Read the Terms for Penalties and Rate Changes
Check each offer for prepayment penalties, mandatory binding arbitration, and whether the rate is fixed or variable. A low starting rate on a variable loan isn't a saving if it can rise, and a prepayment penalty removes your ability to refinance or pay off early.
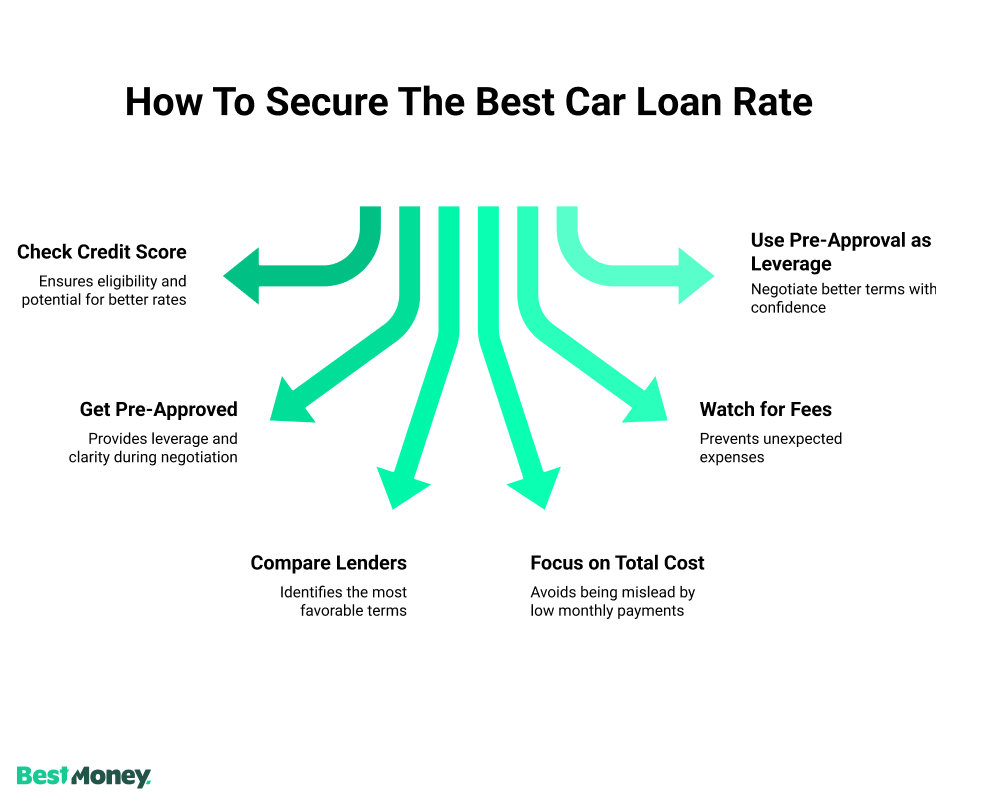
Explore all options: banks, credit unions, online platforms, and dealerships.
Compare rates, terms, fees, and flexibility to find the best option for you.
Use lender competition to your advantage.
Validate lenders through consumer reviews and watchdog sites.
Use pre-approval to benchmark dealer and lender offers.
Ensure pre-approval includes all expected costs.
Align the final contract with pre-approval terms..
Prepayment penalties: Some loans charge fees for early repayment.
Mandatory binding arbitration: Disputes cannot be resolved through the court system.
Variable interest rates: May start low but increase unpredictably.
Contract discrepancies: Ensure all agreements are in writing.
PenFed:
The auto purchase and refinance cash bonus of $200 will apply to loans over $10,000 when the first two recurring payments are made from a PenFed Checking account. Applies to all purchase and refinance loan applications received at PenFed until 12/17/2024; refinance loans must be refinanced from another institution.
PenFed internal refinances and refinance loans originated from 3rd party partners are not eligible for this promotion. A PenFed Checking account does not have to be opened prior to 6/30/2024 but must be used to make the first two recurring payments and remain open until December 1, 2024, to qualify for the bonus.
The loan must be currently active and have the first two recurring monthly payments posted to the auto loan from a PenFed Checking account to qualify for the bonus. The $200 bonus will be deposited to the member’s PenFed Checking or Savings account within 60 days of eligibility completion or by December 1, 2024, whichever is sooner. The promotional bonus will be reported on the year-end Form 1099-INT as taxable income.
PenFed may discontinue or change the promotion at any time. Other restrictions may apply.
Consumer Credit Union Disclaimer:
*To receive this cash bonus, an auto loan must be booked through CCU, and auto purchase must be made at a certified dealer through CCU’s Car Buying Service purchasing process. Auto application must be submitted between 7/01/2026-7/31/2026 and loan funded by 8/31/26 to qualify. Additionally, a minimum loan amount of $10,000 is required to receive this cash bonus. The cash bonus will be awarded in the form of a direct deposit to your CCU checking or savings account within 45 business days from the funding date of the loan. Note: We do not allow lease buyouts or Private Party Purchases.
**APR is Annual Percentage Rate. Rates are subject to change, and can vary based on credit worthiness, CCU Member discounts, age of vehicle, and terms of the loan. Offer subject to credit approval. Rates accurate as of 04/01/2026. Rate applies to 2025 and newer vehicles with a loan term of up to 60 months based on credit worthiness. Call for rates on older model vehicles. Loan amount will be determined by income and other factors. The rate listed includes an additional 0.50% APR discount for buying through our Car Buying Service. To receive this discount, an auto loan must be booked through CCU, and auto purchase must be made at a certified dealer through CCU’s Car Buying Service purchasing process. The rate listed also assumes an automatic payment method. Individual rates may vary based on credit score and other factors. An example of payment terms is as follows: an amount financed of $20,000 with an APR of 3.99% and a term of 60 months would have a monthly payment of $368.00. Call for rates on older model vehicles. Federally insured by NCUA.