Last updatedOctober 2026
Our Best Online Business Checking Accounts October 2026
Set up your business for success
Benefit from top-tier protection, simplified tax prep, and a smooth scale strategy.
Benefit from top-tier protection, simplified tax prep, and a smooth scale strategy.


 Trusted by 15K+ Businesses Nationwide


 Trusted by 15K+ Businesses Nationwide
Choosing the right partner depends on your specific volume and how you plan to use the account. Below, we compared the best business bank accounts by their core strength to help you find the best bank for small business needs, followed by a detailed data comparison.
We evaluate business checking accounts using a scaling-focused framework built for modern companies. Rather than a one-size-fits-all score, we assess how well each bank’s pricing, technology, and support align with different stages of growth.
At BestMoney.com, we understand the importance of making informed financial decisions. Our team of financial experts and editors conducts thorough research across lending, banking, home loans, personal finance, and insurance to provide you with comprehensive comparisons and insights. We continuously update our content to reflect the latest market trends and offerings, ensuring you have access to current, reliable information.
We offer a wide range of services including detailed comparison tools and expert reviews, all designed to meet your specific financial needs. Our mission is to empower you to make confident, well-informed choices that help you achieve your financial goals.
A business checking account is a bank account specifically designed to manage a company’s income and expenses, separate from personal finances. According to the U.S. Small Business Administration, it is a foundational financial tool for businesses of all sizes, from freelancers to established corporations.
Beyond basic transactions, a business checking account serves as the financial hub of an operation. It supports higher transaction volumes, enables multiple users, integrates with accounting software, and helps businesses meet legal, tax, and compliance requirements. Most importantly, it allows owners to separate personal and business finances—an essential step for maintaining liability protection, financial clarity, and long-term growth.
A business checking account helps keep finances organized, supports compliance, and makes it easier to manage and grow your business.
Choosing the best small business checking account starts with understanding how your business actually uses money. Accounts vary widely in fees, transaction limits, and balance requirements, especially if you’re considering a free small business bank account.
The right choice depends on matching your transaction volume and cash needs to the account’s fee structure, so you avoid hidden costs and pay only for what your business truly needs.
This is often the most critical trade-off you will face. Banks generally structure accounts in two ways:
You should estimate your monthly volume of checks, ACH transfers, and teller deposits before deciding. For example, if your volume is high, an account with a waivable maintenance fee is your best bet.
Fees are one of the most important things for you to look at when choosing a business checking account. Banks often advertise accounts as "free," but in reality, they are only free under specific conditions.
If your business handles physical currency, you must watch for cash deposit limits. Most banks allow you to deposit a set amount of cash for free each month (e.g., $5,000). Once you cross that threshold, you may be charged a fee for every $100 deposited. For cash-heavy businesses like retail or food service, this fee can be more expensive than the maintenance fee itself.
While many business checking accounts do not pay interest, some "premium" or "analyzed" accounts do. If you consistently hold a high balance (e.g., $100,000 or more), earning even a modest interest rate can offset other banking costs or fund small perks for your team. Be sure to compare the Annual Percentage Yield (APY) across different institutions to see where your idle cash works hardest for you.
You also need to decide between a traditional bank with physical branches and a digital-only bank.
Whichever path you choose, look for a bank that offers the flexibility to scale. As your transaction volume grows, you want an account that can grow with you without punishing you with unnecessary fees.
“Digital banks often have structural advantages in platform features. Because we're not investing in physical branch infrastructure, we can (and do) focus those resources on building robust digital tools such as multi-user access, detailed cash flow analytics, and the ability to manage multiple sub-accounts for different purposes, like taxes or payroll. These capabilities are essential as businesses grow and need more sophisticated financial management.”
A no-fee business checking account is a business bank account that does not charge a recurring monthly maintenance fee, allowing you to keep more of your revenue focused on operations instead of overhead. Unlike traditional banks, these accounts eliminate the need to track balance minimums to avoid fees, resulting in more predictable and consistent cash flow.
In today’s digital-first business environment, these accounts are more than simple places to store money—they are a core part of your financial tech stack. When comparing options, it’s important to understand the difference between accounts that are truly free and those with fees that are only waived under specific conditions.
When you see a bank advertise $0 monthly fees, it's usually in one of two categories:
Your choice depends on whether you can comfortably guarantee you will meet those requirements every month to avoid the charge.
By going digital, you typically trade physical branch access for better technology and lower costs. Most of these providers offer:
If your business doesn't require frequent cash deposits at a teller window, switching to a dedicated no-fee business checking provider can save you hundreds of dollars in unnecessary bank charges every year while giving you a more powerful toolkit to grow.
“Digital banking is not 'contactless' banking. This is a very human business. We still pride ourselves on delivering the personal service our customers deserve. We strive to meet our customers where they are, versus having them come into a branch, from being available by phone, email, and chat, to now delivering a new AI-powered virtual agent which can provide answers to customer questions 24/7.”
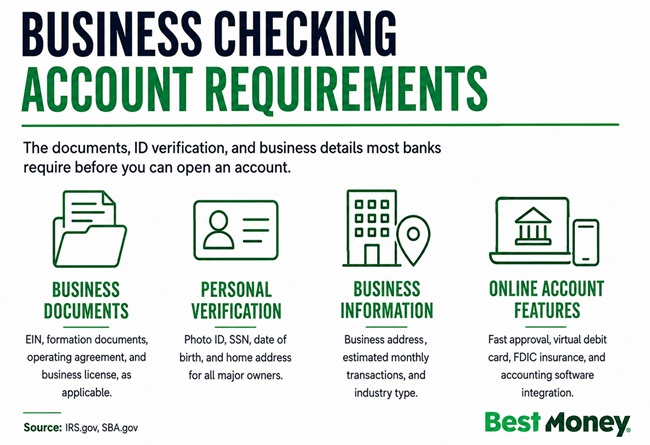
Opening an online business bank account is significantly faster than the traditional branch-based process, often taking between 10 - 15 minutes from start to finish.
However, the speed of your approval depends on having a "digital folder" of paperwork ready to upload.
Modern banks use AI-driven verification to cross-reference your details with state records, so accuracy is key to securing a free business checking account without the wait.
Most banks require the following:
To meet federal identity verification rules, banks will require:
You’ll also need to provide:
To streamline approval and access:
Having these items ready allows you to complete the application in one sitting and potentially fund your account the same day.
“If you’re deciding between a waived-fee account and a no-fee account, consider your primary needs for your business. Online banks often offer no-fee accounts, which might look attractive, but may limit transactions or cash deposits, so extra fees may apply if you exceed those caps. Choosing the account that matches the number of transactions you anticipate monthly, and always review the terms to avoid unexpected charges.”
Lili:
¹ Lili is a financial technology company, not a bank. Banking services provided by Sunrise Banks N.A., Member FDIC.
² The Lili Visa® Debit Card is issued by Sunrise Banks N.A., Member FDIC, pursuant to a license from Visa U.S.A. Inc.
³ The Annual Percentage Yield (“APY”) for the Lili Savings Account is variable and may change at any time. The disclosed APY is effective as of January 13, 2026. Must have at least $0.01 in savings to earn interest. 2.25% APY applies to balances of up to and including $500,000. 4.00% APY applies to balances over $500,000 and up to and including $1,000,000. Any portions of a balance over $1,000,000 will not earn interest or have a yield. Available to Lili plans.
Bluevine:
¹ You can earn $500 when you open a new Bluevine Business Checking account and meet eligibility requirements.
To get your $500 bonus, apply for a Bluevine Business Checking account anytime between now and September 30, 2026 using referral code BM500. After opening your account, deposit a total of $5,000 within the first 30 days. After 30 days, maintain a minimum daily balance of $5,000 while also completing at least one of the following eligibility requirements every 30 days for 90 days:
⁴ No limit on number of transactions. However, checking accounts are subject to the deposit and withdrawal amount limits as set forth in the Bluevine Business Checking Account Agreement.
U.S. Bank:
* Promo code Q4AFL26 MUST be used when opening a U.S. Bank Business Essentials® or Platinum Business Checking account. Limit of one bonus per business. A $25 minimum deposit is required to open one of the referenced accounts.
To earn a business checking bonus, open a qualifying U.S. Bank business checking account between 9/28/2026 and 1/13/2027. Make the required deposit(s) in new money within 30 days of account opening, maintain the same required daily balance through the 60th day, and complete 6 qualifying transactions based on posted date within 60 days of account opening.
Mercury:
*Mercury is a fintech company, not an FDIC-insured bank. Banking services provided through Choice Financial Group and Column N.A., Members FDIC. The IO Card is issued by Patriot Bank, Member FDIC, pursuant to a license from Mastercard®.
The IO Card is issued by Patriot Bank, Member FDIC, pursuant to a license from Mastercard®. To receive cash back, your Mercury accounts must be open and in good standing, meaning they cannot be suspended, restricted, past due, or otherwise in default.
Mercury Treasury is offered by Mercury Advisory, LLC, an SEC-registered investment adviser. This communication does not constitute an offer to sell or the solicitation of any offer to purchase any security. Funds in Mercury Treasury are subject to investment risks, including possible loss of the principal invested, and past performance is not indicative of future results. Please see full disclosures at mercury.com/treasury Mercury Advisory is a wholly-owned subsidiary of Mercury Technologies.
Mercury Treasury is not insured by the FDIC. Funds in Mercury Treasury are not deposits or other obligations of Choice Financial Group or Column N.A., and are not guaranteed by Choice Financial Group or Column N.A.
Eligible Mercury Business users who apply for and maintain a Mercury Personal account may have their Mercury Personal subscription fee waived provided they remain a user on an active Mercury Business account in good standing. Standard Mercury Platform Subscription fees will apply if they no longer meet eligibility requirements, including but not limited to no longer being associated with an eligible Mercury Business account, or if the program is modified or terminated. Mercury may modify or discontinue this offering at any time and will provide notice as required by law. See Subscription Terms for full details.
American Express:
¹Annual Percentage Yield 1.00%. APY as advertised is accurate as of 09/15/2026. APY to be earned on account balances ≤ $500,000. No interest is earned on account balances over $500,000. APY is subject to change at any time without notice before and after a Business Checking Account is opened.
²The following criteria must be met to earn the 35,000 Membership Rewards® points:
(1) Open Your first American Express® Business Checking Account, which is subject to approval;
(2) Deposit a total of $5,000 or more in eligible deposits that you make and areposted to your account within thirty (30) days of account opening. Eligible deposits are all deposits you make, except deposits from any other American Express deposit accounts owned by you, deposits from interest payments, deposits using our Redeem Membership Rewards Points for Deposits feature, and Zelle® payments to and from your American Express® Business Checking accounts. Eligible deposits that you make within thirty (30) days of account opening but that post to your account and appear in your available balance after thirty (30) days of account opening do not qualify;
(3) Maintain an average daily balance in your account of at least $5,000 for sixty (60)days, starting on the date that your eligible deposits are equal to $5,000 or greater.We calculate the average daily balance of your account for the sixty (60) days as thesum of your account’s end-of-day balance for sixty (60) consecutive calendar daysdivided by sixty; and
(4) Complete five (5) qualifying transactions within sixty (60) days of accountopening.
“Qualifying transactions” are defined as mobile deposits, check deposits by mail, and electronic/online transactions including ACH, Wire, and Bill Payment transactions made to or from your account. Qualifying transactions do NOT include the following: Business Debit Card transactions, deposits using our Redeem Membership Rewards Points for Deposits feature, transfers between American Express® Business Checking accountsheld by the same business, transfers to and from American Express® deposit accounts owned by you, Zelle® payments to and from your American Express® Business Checking accounts, or stop payments and transactions that do not post to your account and do not appear in your Available Balance within (60) days of account opening.
³At Allpoint® and MoneyPass® locations in the U.S., you can withdraw cash and get balance information with no fee. Access to ATMs outside of the Allpoint® and MoneyPass® networks are subject to fees by the ATM owner and/or network. ATM withdrawal limits apply. American Express applies foreign exchange fees to withdrawals in foreign currencies. American Express does not accept ATM cash deposits into your Business Checking account at this time. Visit americanexpress.com/atm-locator to find participating ATMs in the U.S.
We are currently accepting applications from eligible U.S. businesses. Not all applicants will be approved for a Business Checking account.
Accounts offered by American Express National Bank, Member FDIC.
Found:
Found is a financial technology company, not a bank. Banking services are provided by Lead Bank, Member FDIC. The funds in your account are FDIC-insured up to $250,000 per depositor for each account ownership category. FDIC insurance only covers the failure of an FDIC-insured depository institution.
*To qualify for the $125 bonus, a user must (1) have a balance of $5,000 in their Found account within 30 days of account creation; and (2) must maintain a minimum balance of $5,000 for 30 days. Account must be opened by 11/30/26. Offer is valid for new customers only and expires 12/31/26. It is valid only when signing up using offer code BESTMONEY. Terms Apply.
**Optional subscriptions to Found Plus for $35/month or $315/year or Found Pro for $80/month or $720/year. Discount rates may apply. There are no monthly account maintenance fees, but other fees such as transactional fees for wires, instant transfers, and ATM apply. Read Found Fee Schedule
Relay:
1. Relay is a financial technology company and is not an FDIC-insured bank. Banking services provided by Thread Bank, Member FDIC. FDIC deposit insurance covers the failure of an insured bank. Certain conditions must be satisfied for pass-through deposit insurance coverage to apply.
1 For Relay Subscription Plans with an interest-bearing deposit account, the interest rate and Annual Percentage Yield on your account are accurate as of 9/17/2026 and are variable and subject to change based on the target range of the Federal Funds rate. Fees may reduce earnings:
• When you are subscribed to the Starter Plan, the interest rate on your savings accounts is 1.18% with an APY of 1.19%.
• When you are subscribed to the Grow Plan, the interest rate on your savings accounts is 1.86% with an APY of 1.87%.
• When you are subscribed to the Scale Plan, the interest rate on your savings accounts is 3.16% with an APY of 3.21%.
Grasshopper:
1. Innovator Business Checking Annual Percentage Yield (APY) is accurate as of 11/03/2025. The minimum amount to open an account is $100.00. Rate tiers are as follows: 1.00% APY applies to balances of $0.01—$24,999.99. 1.35% APY applies to balances of $25,000-$250,000.00. 1.00 APY applies to balances of $250,000.01 and above. Rates may change after the account is opened. Fees may reduce earnings. National average interest rate for interest checking is 0.07% APY – source: www.fdic.gov.
Innovator Money Marketing Savings Annual Percentage Yield (APY) is accurate as of 01/05/2026. The minimum amount to open an account is $100.00. Rate tiers are as follows: 1.55% APY applies to balances of $0.01—$24,999.99. 3.00% APY applies to balances of $25,000 and up. Rates may change after the account is opened. Fees may reduce earnings.
2. Eligible Participants: This promotion is non-transferrable and limited to one offer per new Grasshopper Bank client. (“New Client”) You are not eligible for this offer nor a New Client if you were an owner of an authorized signer on any Grasshopper Bank account within the last twelve (12) months. New Clients must be (i) at least 18 years old; and (ii) a legal resident of the 50 United States or Washington, DC. Employees of Grasshopper Bank as well as the immediate family members (spouse, parents, siblings, and children) and/or household members of each such person are not eligible. Only one Grasshopper Bank account bonus ($300) offer per business owner or authorized signer, regardless of the number of businesses owned or operated by the client. Conditions and Promotional Period: To receive the bonus associated with this promotion, New Clients must meet the eligibility criteria outlined in the preceding section and 1) apply for and open an Innovator Business Checking Account (“Account”) using a bonus offer code between 12:00:00 AM EST on September 1st, 2025 and 11:59:59 PM EST on April 1st, 2026; 2) fund their Account with $10,000 or more of New Money* within thirty (30) days of account opening; and 3) Maintain an average daily balance of $10,000 or greater during the Maintenance Period** into that new eligible Innovator Business Checking Account.
*New Money is new funds deposited into your Innovator Business Checking Account that are not transfers from other Grasshopper Bank accounts
**The Maintenance Period begins thirty-one (31) calendar days after account opening and ends ninety (90) calendar days after account opening.
Notification: If a New Client meets all of the eligibility requirements and conditions of the promotion, Grasshopper Bank will deposit the bonus into their Innovator Business Checking Account by the fifteenth day of the month that follows the month in which the last requirement was met, which is defined as the end of the Maintenance Period, provided that the account is not closed or locked. Limitation of Liability: Grasshopper Bank and its respective officers, directors, employees, representatives and agents shall have no liability and shall be held harmless by participants for any damage, loss or liability to persons or property, due in whole or part, directly or indirectly, because of the acceptance, possession, use or misuse of prize or participation in this promotion. Grasshopper Bank reserves the right in its sole discretion to modify or end the promotion at any time and exclude any participant for any reason, including suspected fraud, misuse, or other misconduct. It may also terminate any Grasshopper Bank accounts you may have with us. Grasshopper Bank also reserves the right to reverse the bonus if a New Client closes their Innovator Business Checking Account within 150 days of opening it. Miscellaneous: The bonus associated with this promotion is considered interest and will be reported on IRS Form 1099-INT. You are responsible for any federal or state taxes resulting from the promotion. Please consult your tax advisor if you have questions about tax treatment.
Capital One:
How do you earn the cash bonus?
Apply for a new Basic or Enhanced checking account online, using the promo code SBOFFER500. Promo code MUST be used when completing the online application.
To become eligible for the offer bonus, you must complete the following qualifying activities on the newly opened Basic or Enhanced checking account:
1) Within 30 days of account opening, deposit at least $5,000 from an external source (cash deposits and funds sourced from an account with another financial institution that was not affiliated with Capital One prior to January 1, 2025, qualify; transfers between Capital One accounts do not qualify); 2) maintain a minimum end-of-day balance of $5,000 for at least 60 days within 90 days of account opening; 3) make 10 qualifying electronic transactions within 90 days of account opening. Qualifying transactions only include electronic wire (credits or debits), electronic remote check deposit, electronic ACH (credits or debits), and instant transfers (credit or debit, from an outside entity not affiliated with Capital One prior to Jan 1, 2025).
When will you get your bonus?
Capital One will deposit the bonus into your new business checking account within 60-90 days of meeting all the offer requirements. The bonus will be reflected on your monthly statement. The amount of the bonus will be reported to the IRS (and state revenue authorities, where required) on IRS Form 1099‑INT for tax year in which you receive the bonus. If your account is in default, closed or suspended, or otherwise not in good standing before you receive the bonus, you will not receive the bonus.
Offer restrictions: 1) Capital One reserves the right to end or change the terms of this offer at any time prior to you accepting the offer, with or without notice. Changing the terms of this offer could result in a change to any of the offer requirements such as, but not limited to, the required deposit amounts, qualifying transactions, or the bonus amounts. 2) Applicants who are users on Capital One Business checking accounts open on or after January 1, 2025 are ineligible for the bonus. 3) Offer applicable for online account openings only. Any account not opened online will not be eligible for the offer. 4) All applications are subject to approval. 5) Only one account per business will be eligible for the bonus offer.
Wells Fargo:
¹How to qualify for this offer
To be Eligible: Offer is for new business checking customers only. Limit one business checking bonus per business and one per business owner within a 24-month period. Only one business checking bonus may be paid per business, regardless of the number of owners. A business owner is not eligible to receive more than one business checking bonus during this period, including across multiple businesses. Only a Wells Fargo Initiate Business Checking®, Navigate Business Checking®, or Optimize Business Checking® account is eligible for this offer. You are not eligible for this offer if you currently own a Wells Fargo business checking account, closed one within the past 90 days, or are an employee of Wells Fargo. Non-resident aliens or foreign entities signing Form W-8 are not eligible for the offer. If Wells Fargo suspects misuse or abuse of this promotional offer, it may close the account and may rescind or not pay the bonus.
To receive the cash bonus: You must use your bonus offer code by November 10, 2026 when opening a new eligible Wells Fargo business checking account, which is subject to approval, and complete the following requirements.
Deposit amount | Cash bonus |
$2,500 - $9,999 | $400 |
$10,000 - $24,999 | $550 |
$25,000 or more | $825 |
The following count as qualifying transactions:
The following don’t count as qualifying transactions:
After the 60-day qualification period, if you have met all offer requirements, we will deposit the bonus into your new account within 30 calendar days. To receive this bonus, the enrolled account must not be closed or restricted at the time of payout. We may close accounts with a zero balance without prior notice. You are responsible for any taxes due on the bonus. We will report the bonus as income to tax authorities, as required by applicable law. If you are subject to backup withholding at the time of payment, we will withhold the required amount and remit to the tax authorities.
Other Terms: This offer may be discontinued or changed at any time without notice and cannot be combined with any other business checking offer. Offer cannot be reproduced, purchased, sold, transferred, or traded.
Talk with a banker or see the "Business Account Fee and Information Schedule” and “Deposit Account Agreement" for complete checking account details, including the applicable monthly service fee and options to avoid it. The actions required to earn this bonus are separate from the actions available to avoid the monthly service fee.
_________________________________________________________________________________________________________________________________________________________________
²Digital wallets may not be available on all devices. Your mobile carrier’s message and data rates may apply.
Zelle® and the Zelle® related marks are wholly owned by Early Warning Services, LLC and are used herein under license.
NBKC:
¹nbkc will reimburse you up to $12/month in fees for out-of-network ATM
²nbkc bank deposits are insured by the FDIC up to $250,000 per depositor. Read more from the FDIC.
Chase for Business
Offer valid 06/24/2026 - 10/15/2026
¹Barlow Research Associates, Inc. Analyst’s Journal article, “Chase Continues to Hold the Number One Primary Bank Market Share Position in Small Business” by Sandy Hanson, published January 8, 2026. Findings reflect primary bank market share among small businesses (annual revenues $100K–<$10mm) 10 using barlow research survey data from 1q2024–4q2025; top bank set determined by two-year primary market share.
²Chase Business Complete Checking® (“Complete Checking”): There is a $15 Monthly Service Fee (MSF) that we’ll waive if you meet any of these qualifying activities for each Complete Checking account in a monthly statement period: (A) Maintain a linked personal Chase Private Client CheckingSM, JPMorgan Classic Checking or Private Client Checking Plus account (the linked personal account owner must be a signer and direct business owner listed on the Complete Checking account), (B) Meet Chase Military Banking requirements or (C) Fulfill at least $2,000 in one Qualifying Activity shown below.
Qualifying Activities: (1) $2,000 Minimum Daily Ending Balance for Complete Checking each business day during the monthly statement period (excluding the last business day); (2) $2,000 Chase Payment Solutions® deposits into Complete Checking (net of chargebacks, refunds, or other adjustments) at least one day before the end of the Complete Checking monthly statement period, using one or more of the following: Chase QuickAccept®, InstaMed® Patient Payments and InstaMed Patient Portal and/or other eligible Chase Payment Solutions products. Eligible deposits must be made from a Chase Payment Solutions account associated with the same business as your Complete Checking account. The cutoff time for eligible deposits is 11:59 p.m. ET one day prior to the last day of your Complete Checking monthly statement period. Deposits are subject to limits, verification, fraud monitoring, and other restrictions; or (3) $2,000 Chase Ink® and/or Chase Sapphire Reserve for Business® card eligible purchases in the most recent monthly card billing cycle, which may be different than your Complete Checking monthly statement period. Eligible purchases must be made using card(s) associated with the same business as your Complete Checking account, and must be eligible to earn Chase Ultimate Rewards® points.
Additional fees for certain transactions and cash deposits may apply. For full Complete Checking product details and fees, please review the Additional Banking Services and Fees for Business Accounts at chase.com/business/disclosures or visit a Chase branch. This information is subject to change. QuickAccept is not available in U.S. territories or outside the U.S. QuickAccept usage subject to eligibility, terms of service, monitoring and further review. QuickAccept is not available to all businesses. Message and data rates may apply from your service provider.
³Eligibility: Offer not available to existing Chase business checking customers, government entities, political action committees, or those with campaign or other political accounts or accounts closed within 90 days of opening or accounts closed with a negative balance within 3 years from account opening. Signers can receive one business checking offer every two years from last offer enrollment date. One offer per account. Employees of JPMorgan Chase Bank, N.A. and affiliates are not eligible.
How to qualify:
1. Open a new Chase Business Complete Checking® account online or at a branch. For Chase Performance Business Checking®, Chase Performance Business Checking® with Interest, Chase Platinum Business CheckingSM, or Not For Profit accounts, visit a branch to open an account. Accounts subject to approval.
2. Deposit the minimum amount shown below in new money (cannot be existing deposits at Chase or affiliates) into your new qualifying checking account within 30 days of offer enrollment and maintain that balance for 60 days from offer enrollment. If your balance falls below the required minimum deposit amount shown below at any time during the 60 days, your offer amount may be reduced or may no longer qualify.
| Business checking offer amount | Required minimum new money deposit amount |
|---|---|
$400 | $2,000 |
$500 | $10,000 |
Airwallex
See Airwallex Terms and Conditions here.