This step-by-step first-time home buyer checklist walks you from your first credit check to the day you get the keys.
Written by
David Kindness
David Kindness is a finance, insurance and tax expert at BestMoney.com. He has written for Investopedia, The Balance, and Techopedia, sharing his deep expertise in taxation, accounting, and finance. A CPA with a Bachelor’s in Accounting, David has worked as a tax specialist and Senior Accountant for high-net-worth clients and businesses in the San Diego area.
In 2025, first-time buyers made up just 21% of the market — a record low. They also put down a median of only 10%, according to theNational Association of Realtors. That makes preparation more important than ever.
Why Does a First-Time Home Buyer Checklist Matter Now?
A first-time home buyer checklist matters now because buying a first home means juggling mortgages, property searches, closing logistics, and a move at once. A smart first step iscomparing purchase mortgage options so you know what you can borrow before you shop.
In 2026, first-time buyers face elevated mortgage rates and tight inventory in many areas. The 30-year fixed rate averaged about 6.67% in August 2026, roughly flat from a year earlier,according to Freddie Mac. A structured checklist helps you avoid missing critical steps.
What Should First-Time Buyers Know First?
Budget beyond the purchase price, including inspections, maintenance, taxes, and insurance.
Build your credit and gather documents one to two years before you buy.
Get pre-approved early to firm up your budget and strengthen your offer.
Explore down payment assistance, grants, and FHA, VA, and USDA loan options.
Lean on a skilled agent, lender, and inspector to avoid costly mistakes.
What's on the First-Time Home Buyer Checklist?
The first-time home buyer checklist covers five phases: financial prep, budgeting, pre-approval, house hunting and offers, and closing. Each phase has concrete actions and a rough timeline.
Most buyers work through these steps over one to two years. Your pace depends on your finances and local market. Use the sections in order, or jump to your current phase.
1. How Do You Assess Your Financial Readiness? (1–2 Years Before)
Start by understanding your credit, your debt load, and how much house you can comfortably afford. These numbers shape every later decision.
Check your credit: review your reports for free atAnnualCreditReport.com, the federally authorized source.
Improve your credit score: pay on time, keep balances low relative to your limits, and avoid new credit before buying.
2. How Do You Build Your Home-Buying Budget? (6–12 Months Before)
Build a budget that covers far more than the purchase price. The extra costs of ownership catch many first-time buyers off guard.
Save for the down payment and closing costs. Down payments typically run 5%–20% of the price, and closing costs about 2%–5%,per CFPB homebuyer resources.
Plan for ongoing costs: maintenance, property taxes, and home insurance all vary by location, home, and value.
Build an emergency fund: set aside a few months of expenses for surprises like a leaky roof or cracked foundation.
Compare loan types: weigh fixed-rate mortgages, suited to long-term buyers, against adjustable-rate mortgages (ARMs).
3. How Do You Get Pre-Approved for a Mortgage? (3–6 Months Before)
Get pre-approved to confirm your borrowing power and show sellers you're serious. Gather your documents and shop several lenders before you commit.
Gather financial documents: recent pay stubs (last 30–90 days), W-2s or tax returns (past two years), and bank and investment statements.
Compare several lenders to find competitive rates and a cost-effective fit for your situation.
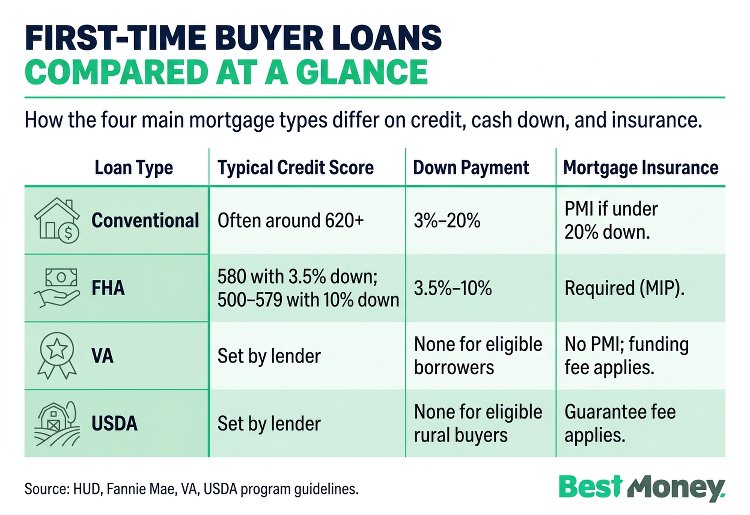
Your options fall into four main loan types: conventional, FHA (Federal Housing Administration), VA (Department of Veterans Affairs), and USDA (US Department of Agriculture). Conventional lenders now weigh yourfull financial picture rather than a single score cutoff, and FHA sets lower minimumsper FHA guidelines. Mortgage insurance (PMI on conventional loans, MIP on FHA loans) protects the lender if you stop paying.
A conforming loan fits limits set by federal regulators; anything above is a "jumbo" loan with stricter terms. For 2026, the baseline conforming limit is $832,750, rising to $1,249,125 in high-cost areas,according to the Federal Housing Finance Agency. Once approved, your pre-approval letter verifies your borrowing power and strengthens your offer.
4. Who Should Be on Your Home-Buying Team?
Assemble professionals who can guide you through the process and protect your interests. The right people help you avoid costly mistakes.
Buyer's agent: choose an experienced professional who specializes in helping first-time buyers.
Real estate attorney: an attorney can review contracts to protect you, and some states require one.
Home inspector: find someone who understands the local climate, weather risks, and the property's age.
Insurance agent: a trustworthy agent can help you get fair rates on coverage you actually need.
Define what you need before you start touring homes. Clear criteria keep your search focused and prevent emotional overspending.
Rank must-haves versus nice-to-haves: separate non-negotiables like location and bedrooms from extras like an updated kitchen.
Research neighborhoods: weigh safety, property-value trends, homeowners association (HOA) rules, and proximity to shopping and schools.
Analyze your commute: test routes during rush hour and consider access to public transportation.
Set a realistic timeline: plan for 30–45 days from accepted offer to closing, plus time for any renovations.
6. How Do You Navigate the House-Hunting Process?
Approach house hunting with a system so details don't blur together after multiple showings. Organization helps you compare options objectively.
Track properties: build a spreadsheet for address, price, features, pros and cons, and your rating. Add photos.
Approach open houses strategically: prepare standard questions and group viewings by area to compare efficiently.
Ask revealing questions: inquire about the age of major systems, recent repairs, utility costs, and why the sellers are moving.
Look beyond cosmetics: focus on structure, natural light, noise, and floor plan rather than décor you can change.
7. How Do You Make a Competitive Offer?
Craft an offer that stands out while still protecting your interests. Your agent can help you balance strength and safety.
Include an earnest money deposit: this good-faith deposit is held in escrow and applied to your costs at closing.
Use contingencies strategically: keep essential financing and inspection contingencies, but consider waiving less critical ones in competitive markets.
Add a brief offer letter: when appropriate, share an authentic note about why you love the home.
Adapt to conditions: consider escalation clauses in seller's markets, or use comparable recent sales (comps) to justify lower offers in buyer's markets.
Prepare a counteroffer plan: decide with your agent which terms are flexible so you can respond quickly.
8. What Due Diligence Do You Complete Once Under Contract?
Once your offer is accepted, verify the home's condition and value before you commit. Due diligence protects you from expensive surprises.
Maximize your home inspection: attend the 2–3 hour inspection and ask questions. Your inspector may recommend specialized checks.
Get a home appraisal: your lender orders an appraisal to confirm value. If it comes in low, you can renegotiate or walk away.
Read seller disclosures carefully: compare what's disclosed with your inspector's findings to spot gaps.
Negotiate repairs or credits: focus on safety issues and major systems first. A closing-cost credit often beats seller-made repairs.
9. How Do You Prepare for a Smooth Closing?
Prepare for closing by confirming the home's condition, ownership, and your funds. Small oversights here can delay your keys.
Schedule a final walk-through: verify that agreed repairs are complete and the home matches its promised condition.
Confirm the title and title insurance: a title company confirms clear ownership and protects you and your lender.
Gather documents and ID: bring a government-issued ID, a cashier's check for closing costs, and proof of homeowners insurance.
Understand who pays what: closing costs are split between buyer and seller, as covered in Step 2 above.
10. What Should You Do After Closing? (Your First Steps as a Homeowner)
Your work isn't over once you have the keys. A few first steps protect your investment and your safety.
Secure your property: replace all locks and update security codes immediately after receiving keys.
Set up essential services: transfer utilities into your name and arrange internet and waste removal before moving in.
Create a maintenance calendar: schedule seasonal upkeep and consider a home warranty for major systems.
Apply for tax exemptions: file with your county assessor to lower your taxable value, depending on your state.
Locate critical components: find your main water shut-off, circuit breaker box, and gas shut-off for emergencies.
Who Is This Guide For?
This checklist fits most people entering the housing market, whatever your starting point. Use the profiles below to find the most relevant starting point for your situation.
Are You Buying Your First Home?
Start at Step 1 and give yourself one to two years to build your credit and savings.
Are You Returning After Years Away?
Revisit today's rates, loan limits, and documentation rules before you shop, since they change often.
Are You Working With a Tight Budget?
Explore down payment assistance, grants, and FHA loans to lower the cash you need upfront.
Are You a Veteran or Service Member?
A VA loan may let you buy with no down payment and no PMI.
Are You Buying in a Rural Area?
A USDA loan may offer zero down payment on qualifying rural properties, subject to income limits.
Your Questions, Answered (FAQs)
What requirements are needed for a first-time home buyer?
You'll generally need a qualifying credit score for your loan type, a manageable debt-to-income ratio, a down payment, and proof of steady income. Requirements vary by loan program.
What are the first things I should do when I buy a house?
Right after closing, change the locks, set up utilities, and locate your main shut-offs. Then start a maintenance calendar, as outlined in Step 10 above.
How much do first-time buyers put down?
The median first-time down payment was 10% in 2025, per theNational Association of Realtors. Many loans allow 3%–3.5% down, and some VA and USDA loans allow zero down.
How long does it take to buy a house?
Plan for roughly 30–45 days from an accepted offer to closing, plus preparation time beforehand. Your credit and savings work can begin one to two years earlier.
Why Trust BestMoney?
You can trust this guide because it was written by David Kindness, a finance, insurance, and tax expert at BestMoney.com. He has written for Investopedia, The Balance, and Techopedia on taxation, accounting, and finance.
David is a CPA with a bachelor's in accounting. He has worked as a tax specialist and senior accountant for high-net-worth clients and businesses in the San Diego area. Our editorial team reviews and compares financial products to help you make informed decisions.
How We Researched This
We built this guide from authoritative secondary sources rather than a proprietary BestMoney survey. We reviewed the 2025 Profile of Home Buyers and Sellers, the FHFA's 2026 conforming loan limits, FHA loan requirements, and CFPB homebuyer resources. Where figures involve rates or program rules, we cite the primary source inline so you can verify current details.
Where We Got Our Information
The sources below are linked inline where each figure appears, and are listed here for transparency:
National Association of Realtors — 2025 Profile of Home Buyers and Sellers.
Freddie Mac — Primary Mortgage Market Survey (mortgage rate data).
Federal Housing Finance Agency — 2026 Conforming Loan Limit Values.
US Department of Housing and Urban Development — FHA loan requirements.
Fannie Mae — Selling Guide announcement (SEL-2025-09).
Consumer Financial Protection Bureau —Owning a Home homebuyer resources.
AnnualCreditReport.com — free credit reports.
What Should You Do Next as a First-Time Buyer?
Your next step is to turn this plan into action. You now have a roadmap: prepare your finances, assemble the right team, set clear priorities, and make well-protected offers. In 2026's competitive market, a strong pre-approval and smart contingencies help your offer stand out.
From here, take these concrete steps:
Compare pre-approval requirements across several lenders to firm up your budget.
Track mortgage rates so you can act when the timing fits.
Written byDavid Kindness
David Kindness is a finance, insurance and tax expert at BestMoney.com. He has written for Investopedia, The Balance, and Techopedia, sharing his deep expertise in taxation, accounting, and finance. A CPA with a Bachelor’s in Accounting, David has worked as a tax specialist and Senior Accountant for high-net-worth clients and businesses in the San Diego area.