Freedom Debt Relief vs. National Debt Relief: Which Debt Settlement Company Is Better in 2026?
Freedom Debt Relief vs. National Debt Relief: Which Debt Settlement Company Is Better in 2026?
Both charge about 15% to 25% of enrolled debt, but their support style and legal history differ. Here's how to pick.
Written by
Maya Dollarhide
Maya Dollarhide is a writer specializing in personal finance, with a special focus on student loans and debt consolidation and management. She has written for Yahoo Finance, Investopedia, Student Loan Hero, Bankrate, and other publications.
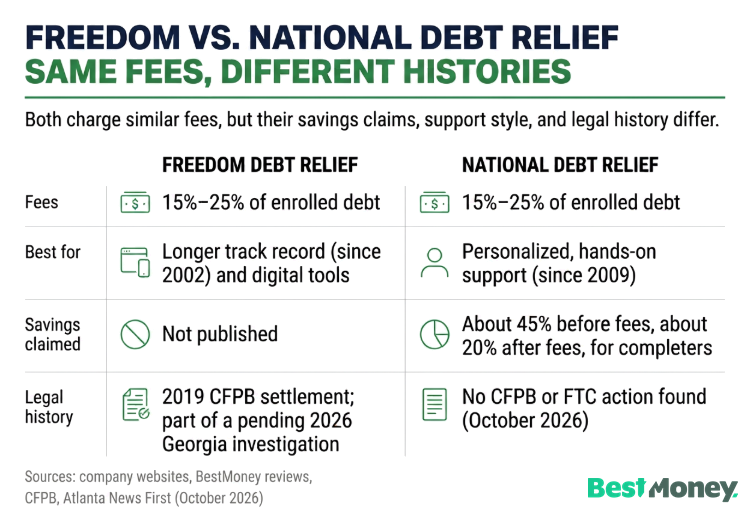
In the Freedom Debt Relief vs. National Debt Relief matchup, both companies offer similar debt settlement services. National Debt Relief emphasizes personalized support, while Freedom Debt Relief offers a longer track record and digital tools.
Struggling with high-interest credit card balances and other unsecured loans? Adebt settlement company may help you reduce what you owe and regain control.
Weighing Freedom Debt Relief vs. National Debt Relief starts with fees, credit impact, and legal history. You can alsocompare debt relief companies side by side.
Freedom Debt Relief, which its website says is affiliated with Achieve, and National Debt Relief are both accredited debt settlement providers. These companies negotiate with creditors toreduce credit card debt, personal loans, medical bills, and other unsecured debt.
While their core approach is similar, there are key differences in program structure, customer experience, and legal history.
This guide provides twosettlement company comparisons, the pros and cons, customer reviews, and costs to help you decide based on your financial situation.
What Are the Key Takeaways From This Comparison?
The two companies run similar programs, so your choice comes down to support style, track record, and legal history.
National Debt Relief may suit people who want personalized support.
Freedom Debt Relief may suit people who want a longer track record and digital tools.
Both charge about 15%–25% of enrolled debt, per Freedom Debt Relief's website and BestMoney's National Debt Relief review.
National Debt Relief says completers save about 45% before fees, or about 20% after fees.
Settled accounts can stay on your credit report for seven years, according to Experian.
Freedom Debt Relief settled with the CFPB in 2019 and is part of a pending 2026 Georgia investigation.
Which Is Better: Freedom Debt Relief or National Debt Relief?
Neither company is better for everyone. National Debt Relief may fit you if you want hands-on support. Freedom Debt Relief may fit you if you value its longer history and online tools.
Before you go this route, understand what happens to your credit. Settled accounts show you didn't pay the full balance, so settlement tends to make more sense if you're already behind on payments.
How Do Freedom Debt Relief and National Debt Relief Compare at a Glance?
BestMoney compared the two companies using their websites, our reviews of each, BBB profiles, and CFPB and FTC records, checked in October 2026.
Company
Freedom Debt Relief
National Debt Relief
Founded
2002
2009
Minimum debt required
$7,500
$7,500 (per BestMoney's review)
Typical fees
15%–25% of enrolled debt, per its website
15%–25% of enrolled debt (per BestMoney's review)
Savings claimed
Not published
About 45% before fees, or about 20% including fees, for completers
No CFPB or FTC action found (checked October 2026)
What Should You Know About Freedom Debt Relief?
Freedom Debt Relief is a long-running debt settlement company that's operated since 2002. Its website reports it has served over a million clients and says it's affiliated with Achieve.
The company doesn't publish its average settlement percentage online. The company says it may also help with some other debts, including private student loans and business debt, under certain conditions.
Pros:
Established company with more than two decades of experience
Track record of negotiating with major creditors since 2002
Online dashboard for tracking progress, available 24/7, according to its website
Access to debt specialists, the company says
Cons:
Your credit score can drop during the program
Creditors aren't required to agree to a settlement
Settled a CFPB lawsuit in 2019 and is part of a pending 2026 Georgia investigation
[Product widget: Freedom Debt Relief — VISIT SITE — https://www.bestmoney.com/v?product_id=2057]
What Should You Know About National Debt Relief?
National Debt Relief says it emphasizes transparent, personalized support. According to its website, clients who complete the program save about 45% before fees, or about 20% including fees, over 24–48 months.
The company's website also says more than 1.5 million people have enrolled since 2009. According to BestMoney's National Debt Relief review, the program requires at least $7,500 in debt and charges 15%–25% fees. The company says it can also help with repossessions and private education loans.
Pros:
BBB customer review score of about 4.69/5 (Sept 2026)
Educational resource page
Says it explains timelines upfront
Online portal for managing your account, according to BestMoney's National Debt Relief review
Phone consultation with a debt specialist, according to BestMoney's National Debt Relief review
Cons:
Program timelines can run up to four years
Creditors aren't required to settle
[Product widget: National Debt Relief — VISIT SITE — https://www.bestmoney.com/v?product_id=1965]
How Do Debt Settlement Companies Work?
Both companies follow a similar five-step process: you save into a dedicated account while the company negotiates lower payoffs with your creditors. Think of the account as a savings jar you fill each month, then empty to pay each negotiated deal.
Free consultation: Speak with a debt specialist by phone to review your finances and decide if it's the right fit.
Dedicated account: Open an FDIC-insured savings account that holds money for settlement payments and fees.
Paused payments: Stop paying your creditors temporarily while the company negotiates on your behalf.
Creditor negotiation: The company works directly with your creditors to reduce your outstanding balances.
Settled debts: Once deals are reached, funds from your account pay the settled amounts and program fees.
The two companies have similar stated fee ranges and debt minimums but differ on tools, reviews, and legal history. Let's take a closer look at their similarities and differences.
What Fees and Costs Should You Expect?
Both companies charge about 15%–25% of enrolled debt, per Freedom Debt Relief's website and BestMoney's National Debt Relief review.
The FTC'sTelemarketing Sales Rule guide bars debt relief companies from collecting fees before they settle a debt. You must also make a payment under that deal first.
If a company asks for payment upfront, treat it as a red flag and learnhow to avoid loan scams.
Here's what to expect:
Settlement fees: The fee comes out of your account only after a debt is settled and you've paid under that deal.
Dedicated account fees: The third-party company that holds your account may charge setup and monthly fees, which vary.
Fee schedules: Ask either company for a full written fee list before you enroll.
Tax implications: Forgiven debt is generally taxable income, so plan for it (see the tax question in our FAQ below).
Here's an illustrative example based on the 15%–25% fee range both companies charge. If you enroll $20,000, the fee comes to $3,000–$5,000.
Using National Debt Relief's stated averages, a 45% reduction would cut that balance by about $9,000 before fees. After a $5,000 fee, your net savings would be about $4,000, or 20%.
How Do Their Online Tools and Support Differ?
Freedom Debt Relief leans on digital tools, while National Debt Relief leans on personalized support.
Freedom Debt Relief offers an online client dashboard with 24/7 access, according to BestMoney's Freedom Debt Relief review.
National Debt Relief clients manage their accounts on an online portal, according to BestMoney's National Debt Relief review.
Who Is Eligible, and How Much Debt Do You Need?
Both companies require at least $7,500 in unsecured debt, per Freedom Debt Relief's website and BestMoney's National Debt Relief review. You'll also need to show financial hardship, such as job loss, reduced income, or a high debt-to-income ratio.
BestMoney's Freedom Debt Relief review notes the company doesn't provide relief for federally backed student loans or secured debt. The FTC says for-profit companies typically offer settlement programs to people with significant credit card debt.
Secured debts, such as mortgages, auto loans, and secured lines of credit
Federal student loans
How Do Customer Reviews and Reputation Compare?
Both companies hold an A+ rating from the Better Business Bureau (BBB). Freedom Debt Relief'sBBB profile shows an A+ and accreditation since 2015. National Debt Relief holds an A+ on itsBBB customer reviews profile.
National Debt Relief's BBB profile showed about 4.69 out of 5 stars from about 5,747 reviews as of September 2026.
Freedom Debt Relief's BBB profile doesn't publish a star score, so read its recent reviews directly before you decide. In scale, Freedom Debt Relief reports serving over one million clients, while National Debt Relief reports more than 1.5 million enrollees.
[Product widget: Accredited Debt Relief — VISIT SITE — https://www.bestmoney.com/v?product_id=2479]
Has Either Company Faced Legal or Regulatory Action?
Yes, Freedom Debt Relief has a 2019 CFPB settlement and is part of a pending 2026 Georgia investigation. For National Debt Relief, we found no CFPB or FTC action.
2019 settlement: Thecase settled in 2019 with $20 million in restitution and a $5 million civil penalty.
Georgia investigation: PerAtlanta News First, the AG's consumer protection division confirmed Turnbull Law Group and Freedom Debt Relief are part of a pending investigation.
Investigation status: No findings or charges have been reported as of that March 2026 report.
Freedom Debt Relief's role: The same report says Freedom Debt Relief provides non-legal administrative services to Turnbull, including answering and routing calls.
National Debt Relief: We found no CFPB orFTC action naming National Debt Relief in the agencies' public lists (checked October 2026).
How Does Debt Settlement Affect Your Credit Score?
Debt settlement hits your credit score hard. While you're in either program, common consequences may include:
Who Wins the Freedom Debt Relief vs. National Debt Relief Matchup?
National Debt Relief could suit many people in 2026, given its published BBB review score and no CFPB or FTC action found.
Freedom Debt Relief remains a strong contender if you prefer a longer operating history and an online platform. Weigh its legal history, covered above, before you enroll.
National Debt Relief may be a good choice if you:
Want a personalized approach with more conversation with debt specialists
Prefer a company with no CFPB or FTC action found
Value a published BBB customer review score you can check
Freedom Debt Relief may appeal if you:
Prefer a company that's offered debt settlement support since 2002
Plan to manage your account with digital tools, such as 24/7 settlement tracking, according to its website
In practice, the main difference shows up in customer experience. National Debt Relief says it emphasizes personalized service, while Freedom Debt Relief leans on digital tools.
What Are the Alternatives to Debt Settlement?
Debt management plans and debt consolidation loans are two common alternatives. Both can simplify payments without settling for less than you owe.
How Do Debt Management Plans Work?
Offered by nonprofit credit counseling agencies,debt management plans combine multiple debts into one payment. The FTC's guide onhow to get out of debt says a good credit counselor reviews your specific financial situation, then offers customized advice.
When Does a Debt Consolidation Loan Make Sense?
A consolidation loan makes sense when your credit and finances are strong enough to qualify.A debt consolidation loan can turn multiple payments into one, sometimes at a lower interest rate.
Options include a personal loan, a secured line of credit, or a 0% intro APR balance transfer credit card.
Who This Guide Is For
If you're already behind on payments and owe $7,500 or more in unsecured debt, compare these two programs.
If you're current on payments, a debt management plan or consolidation loan may protect your credit better.
If you mainly owe secured or federal student loan debt, settlement likely won't cover it.
If neither company serves your state, check each provider's eligibility page before you rule out settlement.
Your Questions, Answered (FAQs)
Which is better, National Debt Relief or Freedom Debt Relief?
Both offer similar programs, so the better fit depends on your needs. National Debt Relief emphasizes personalized support, while Freedom Debt Relief has operated longer and offers more digital tools.
Is National Debt Relief legit?
National Debt Relief holds an A+ BBB rating and ACDR and IAPDA accreditations, and we found no CFPB or FTC action naming it. Still, read your agreement and fee terms before you enroll.
Is Freedom Debt Relief legit?
Freedom Debt Relief has operated since 2002, holds an A+ BBB rating, and lists ACDR and IAPDA accreditations on its website. It settled a CFPB lawsuit in 2019 and is part of a pending 2026 Georgia investigation, so review that history first.
Does debt relief affect my taxes?
Canceled debt is generally taxable income, with some exceptions such as insolvency, according toIRS Topic 431. Lenders generally file aForm 1099-C when they cancel $600 or more, but that's a reporting threshold, so smaller amounts can still be taxable. Consider asking a tax professional before you settle.
How long does the program take?
Both programs typically run 24–48 months, according to BestMoney's reviews of each company, depending on your total debt and monthly deposits.
Why Trust BestMoney?
Maya Dollarhide, a consumer lending expert, is a writer specializing in personal finance, with a focus on student loans, debt consolidation, and debt management. She has written for Yahoo Finance, Investopedia, Student Loan Hero, Bankrate, and other publications.
How We Researched This
BestMoney's editorial team built this comparison from secondary sources, not a proprietary survey. We reviewed both companies' websites, our reviews of each company, both BBB profiles, and FTC, CFPB, IRS, and Experian guidance.
We also checked news reports on Freedom Debt Relief's legal matters and searched CFPB and FTC public enforcement lists. All figures reflect what we found as of October 2026.
Where We Got Our Information
Freedom Debt Relief website, company facts and fees (checked October 2026)
National Debt Relief website, enrollment and savings figures (checked October 2026)
BestMoney, Freedom Debt Relief review and National Debt Relief review (July 2026)
Better Business Bureau, Freedom Debt Relief profile (checked October 2026)
Better Business Bureau, National Debt Relief customer reviews profile (September 2026)
Consumer Financial Protection Bureau, 2017 lawsuit announcement and 2019 settlement page for Freedom Debt Relief
Federal Trade Commission, Debt Relief Services and the Telemarketing Sales Rule guide
Federal Trade Commission, How To Get Out of Debt consumer guide
Federal Trade Commission, debt relief enforcement page (checked October 2026)
Internal Revenue Service, Topic No. 431 and About Form 1099-C
Experian, How Long Do Settled Accounts Remain on a Credit Report? (May 2025)
Atlanta News First, "Atlanta woman cancels debt relief contract following investigation into fees" (March 10, 2026)
Practical Next Steps
Both companies charge about 15%–25% of enrolled debt, so compare written fee schedules before you choose. The two differ mainly on support style, published review scores, and legal history.
List your unsecured debts and confirm you owe at least $7,500 in eligible accounts.
Read our full Freedom Debt Relief and National Debt Relief reviews, and request each company's written fee schedule.
Maya Dollarhide is a writer specializing in personal finance, with a special focus on student loans and debt consolidation and management. She has written for Yahoo Finance, Investopedia, Student Loan Hero, Bankrate, and other publications.