What Documents Do You Need to Apply for a Personal Loan?
What Documents Do You Need to Apply for a Personal Loan?
Having all documents organized beforehand speeds up approval and helps you avoid delays during the application process.
Written by
Brian Acton
Brian Acton is a seasoned personal finance journalist at BestMoney.com who specializes in loans and debt consolidation. His work has appeared in The Wall Street Journal, TIME, USA Today, MarketWatch, Inc. Magazine, HuffPost, and other notable outlets.
What documents do you need to apply for a personal loan? In most cases, lenders want proof of identity, income, address, and banking details, plus a completed application. Those files sit alongside your credit report when the lender decides whether to approve you and on what terms.
Use this checklist first, then compare lenders once your paperwork is ready. When you want a side-by-side view of offers, start withcomparing personal loan options.
What Are the Key Insights About Personal Loan Documents?
Core docs usually include government ID, income proof, address proof, and banking details or SSN/ITIN.
Self-employed borrowers may use tax returns, 1099s, and multi-month bank statements instead of pay stubs, based on common lender checklists.
Confirm each lender's checklist first; needs change with loan purpose, amount, and employment type.
What Documents Do You Need to Apply for a Personal Loan?
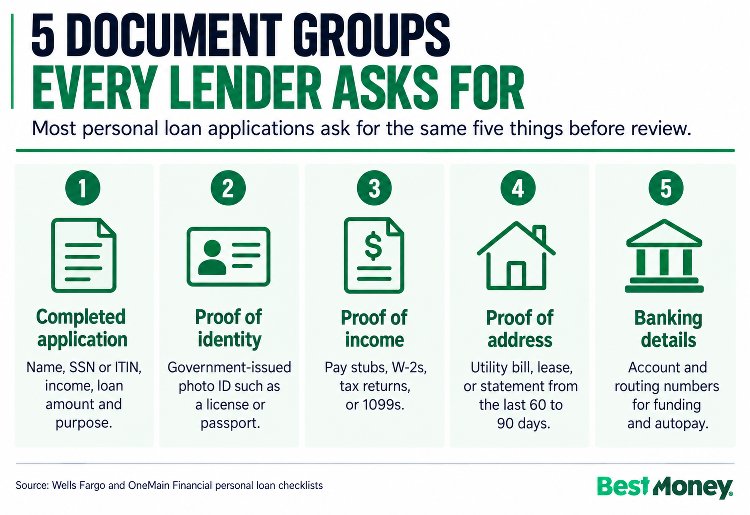
Most personal loan applications ask for five document groups: the application, proof of identity, proof of income and employment, proof of address, and banking details for funding. Lenders use these files to verify who you are and whether you can repay, then review credit.
Banks and similar institutions generally confirm your name, date of birth, address, and ID number before opening a relationship, under31 CFR 1020.220. Think of it like an airport ID check: the lender has to confirm you are who you say you are before moving forward. Your exact checklist still varies by lender, product, and how you earn income.
What Goes on the Loan Application?
A loan application usually includes your name, Social Security number or ITIN, date of birth, contact information, income, loan amount, and loan purpose.
Lenders usually accept a government-issued photo ID, and some may also request a second supporting document.
State-issued driver's license or ID card
Valid passport
Military ID
Social Security card
Birth certificate
Certificate of citizenship
Upload clear, uncropped images so names, numbers, and expiration dates are easy to read. Match the name on your ID to the name on your application whenever you can. Identity checks support the same customer-identification goals outlined in 31 CFR 1020.220.
How Do You Prove Income and Employment?
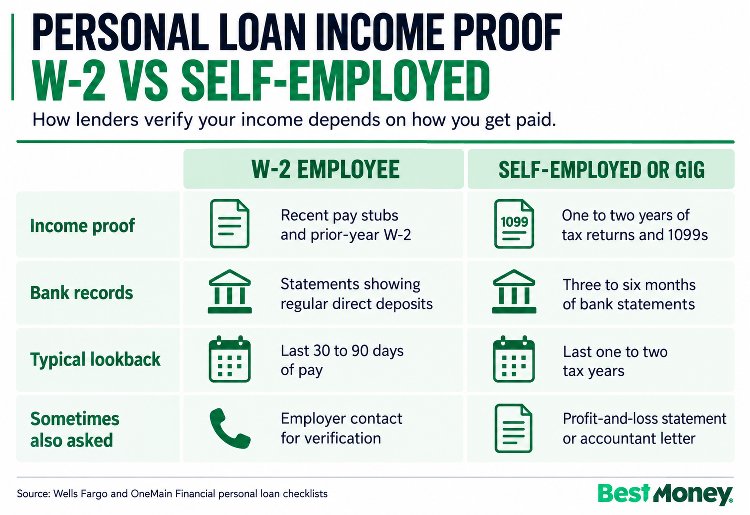
You usually prove income and employment with pay stubs, W-2s, tax returns, 1099s, bank statements, or employer verification. The mix depends on how you get paid.
Borrower type
Common documents
Typical lookback
Optional extras
W-2 employee
Pay stubs, W-2s, bank deposits, employer contacts
Often last 30–90 days of pay; recent tax year forms
Multi-year work history if requested
Self-employed, freelance, or gig
Tax returns, 1099s, bank statements
Often 1–2 years of returns; 3–6 months of statements
Profit-and-loss statement or accountant letter
Lender-facing guides such as OneMain's documents overview and Wells Fargo's checklist list pay stubs, W-2s or tax returns, and related income files among items that may be requested after review.
What Do W-2 Employees Usually Provide?
W-2 employees often share recent pay stubs, prior-year W-2 or 1099 forms, tax returns, bank statements with direct deposits, and employer contact details.
What Do Self-Employed or Gig Workers Usually Provide?
Self-employed, freelance, or gig workers often share one to two years of tax returns, 1099s, and three to six months of bank statements instead of traditional pay stubs. Some lenders also ask for a profit-and-loss statement. Keep labels consistent across tax years and accounts so the lender's review team can follow the deposits without guessing.
What Counts as Proof of Address?
Proof of address usually includes a recent utility bill, lease, mortgage statement, or bank statement showing your address.
Utility bill (electricity, gas, water, or internet)
Rental agreement or mortgage statement
Voter registration card
Bank or credit card statement that shows your address
Many lenders prefer a document dated within about the last 60–90 days. If you moved recently, some also ask for your prior address so it lines up with your credit file. Check the lender's own checklist for the exact window.
What Banking Information Do You Need?
If you want funds by direct deposit or want autopay set up at closing, you'll share banking details:
Bank account number
Bank routing number
Some lenders also let you connect a bank account so they can confirm balances and deposit history, or you can upload statements instead. Connecting may help some lenders verify information more quickly than waiting on micro-deposits; uploading statements works when you prefer not to link an account. Choose the path your lender supports and that you're comfortable with. See primary lender application materials for examples of how banking and income fields appear in a real application flow.
When Do Lenders Ask for Extra Documents?
Lenders may request extra files when your loan purpose, collateral, or applicants go beyond a standard unsecured application. Build these items only if they apply to you.
What If You're Consolidating Debt?
If you're using the personal loan to pay other creditors, bring details on the debts you want to clear:
Current balances
Account numbers for each debt
Creditor contact information and account details
Starting with ID and income proof still matters; adding payoff statements helps the lender see exactly what you plan to consolidate.
What If the Loan Is Secured?
Secured personal loans require collateral the lender can claim if you default. For secured loans, plan to provide:
A detailed description of the collateral
Current market value of the asset
Ownership or value proof such as appraisals, titles, or receipts
What If You Apply With a Cosigner or Joint Borrower?
Other standard application documents the lender lists
How Can You Avoid Document Delays?
You can avoid document delays by confirming the lender's checklist, uploading clear complete files, and responding quickly to follow-up requests. Common delays often come from unclear files, mismatched details, or slow replies, not from missing a rare form.
Confirm the lender's current document checklist (site FAQ, application portal, or a quick call).
Scan or photograph pages so every corner, name, and number is legible and right-side up.
Match legal names, addresses, and income figures across the application, ID, and bank or tax forms.
Upload complete multi-page PDFs when a statement has more than one page.
Respond quickly if the lender asks for a clearer image or one more statement.
A complete first upload may help avoid delays caused by follow-up document requests.
Why Do Personal Loan Document Requirements Vary?
Core identity, income, address, and funding documents show up almost everywhere, but extras change with the product and your profile. Requirements often shift based on:
Loan purpose (debt consolidation, home improvement, major purchase, and similar uses)
Employment type (W-2 employee versus self-employed or gig income)
Loan amount (larger amounts may trigger deeper income or asset review)
Security type (secured versus unsecured)
What Else Do Lenders Review Besides Documents?
Your documents are only one part of the lender's review process. Lenders also weigh:
Credit history and credit score
Debt-to-income (DTI) ratio and other monthly obligations
Income stability and how long you've held the same job or business
Stated loan purpose and whether it fits the product
Documents support the numbers you claim; credit and DTI help lenders evaluatepersonal loans for all credit scores. Self-employed applicants, including high earners with complex returns, may need bank statements or multi-year tax filings so income is clear beyond a single form.
Many lenders pair document prep with a soft credit check and rate preview so you can review terms before a hard application. Finish your packet first, then compare offers when you're ready to apply.
Who Is This Guide For?
This guide is for first-time applicants, self-employed borrowers, debt consolidators, and shoppers comparing loan options before they apply.
First-time applicants building a complete packet before they apply
Self-employed, freelance, or gig workers who need income alternatives to pay stubs
Borrowers consolidating card or loan balances who must list payoff details
Shoppers comparing online personal loan offers and want fewer verification surprises
Your Questions, Answered (FAQs)
What documents are required for a personal loan?
You'll usually need ID, income proof, address proof, and banking details, plus a completed application. See the full five-group checklist above under what documents you need to apply for a personal loan.
Can I get a personal loan without pay stubs?
Often yes, if you can prove income another way. See the self-employed path under how you prove income and employment for common alternatives.
Can I submit documents digitally for my personal loan application?
Yes, most lenders accept digital uploads through online portals. Make sure scans or photos are clear, legible, and properly oriented before you submit.
How long should I keep my personal loan documents?
A common practice is to keep loan documents for the life of the loan and for several years after payoff, though retention needs vary by situation. That often includes the agreement, payment records, and key lender correspondence.
What else do lenders look at when approving a personal loan?
Beyond paperwork, lenders review credit, debt-to-income, income stability, and loan purpose. See what else lenders review besides documents for the full list.
Why Should You Trust BestMoney on This?
This guide was written by Brian Acton, a BestMoney personal finance journalist who covers loans and debt consolidation. For this refresh, we cross-checked identity rules in 31 CFR 1020.220, compared primary lender checklists from Wells Fargo and OneMain Financial, and retained structure from BestMoney's prior educational checklist on this topic. BestMoney publishes personal finance content, including lender-comparison pages and educational guides, so readers can prepare paperwork and review options before they apply.
How We Researched This
This guide is based on published lender information and outside research, not a new BestMoney survey. We reviewed the prior BestMoney documents checklist, primary lender application materials from Wells Fargo and OneMain, and the federal CIP framework via the Legal Information Institute. We also scanned high-ranking educational and lender pages for structure only and noted common borrower questions from search and AI answer patterns.
What Should You Remember About Personal Loan Documents?
What documents do you need to apply for a personal loan? Plan on ID, income proof that matches how you earn, address proof, banking details, and a complete application. Add payoff statements for consolidation, collateral files for secured loans, and a full second packet if you apply with a cosigner. Confirm the lender's list, upload clear files, and keep names and numbers consistent so review can move without extra back-and-forth.
What Should You Do Next?
Next, gather your documents, compare lenders, and review expected approval timelines.
Assemble your core packet: ID, income proof for your job type, address proof, and banking details.
Compare lender offers and eligibility criteria side by side before you submit a hard application.
Brian Acton is a seasoned personal finance journalist at BestMoney.com who specializes in loans and debt consolidation. His work has appeared in The Wall Street Journal, TIME, USA Today, MarketWatch, Inc. Magazine, HuffPost, and other notable outlets.