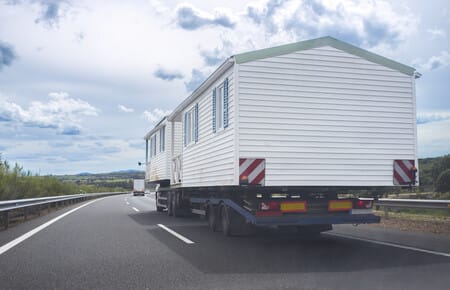
Manufactured homes are factory-built to federal HUD Code standards and offer one of the most affordable paths to homeownership in the U.S. today.
Written by
Patrick Sather
Patrick Sather is a personal finance expert at BestMoney.com, specializing in online banking. He is an award-winning writer and licensed broker who has worked at leading financial firms such as TD Ameritrade and Pacific Life. With degrees in Economics, International Trade, and English from the University of Nebraska, Patrick delivers practical advice on financial decisions.
If you're priced out of the traditional housing market, manufactured homes may offer a realistic path to homeownership. A new manufactured home averages about $123,300 — less than one-third the cost of the average site-built home at $405,939 (Manufactured Housing Institute). That price gap makes manufactured housing the largest source of unsubsidized affordable housing in the country.
Whether you're a first-time buyer, looking to downsize, or exploring options for rural land you already own,comparing mortgage lenders is a smart first step. A manufactured home mortgage works like any other home loan when you own the land and the home carries a HUD certification label—but the options and requirements differ, so understanding your choices matters.
Key Insights
A manufactured home is factory-built to federal HUD Code standards, not local building codes.
New manufactured homes average about $123,300 — under one-third the cost of a site-built home.
A 2026 federal law removed the permanent-chassis requirement; 2025 HUD updates allow multi-unit homes.
Financing depends on land ownership: mortgage if you own the land, chattel loan if you don't.
"Mobile home" means pre-1976; "manufactured home" means built after June 15, 1976.
What Is a Manufactured Home?
A manufactured home is a prefabricated home built entirely in a factory to the federal Manufactured Home Construction and Safety Standards, commonly known as the HUD Code. Unlike traditional site-built homes constructed on-site with a permanent foundation, manufactured homes are assembled on a steel chassis and transported to their installation site.
The key distinction is the building code. Manufactured homes must meet nationalHUD standards, while modular and site-built homes follow state and local building codes. Every manufactured home built after June 15, 1976 carries a red HUD certification label—a federal seal confirming the home meets construction and safety requirements.
In 2026, the21st Century ROAD to Housing Act removed the permanent-chassis requirement from the federal definition of a manufactured home, giving manufacturers more flexibility in design and construction. Combined with 2025 HUD Code updates that allow multi-unit manufactured homes, these changes are intended to lower production costs and expand the kinds of manufactured housing that can be built.
What's the History Behind Manufactured Homes?
Prior to June 15, 1976, factory-built homes were known as mobile homes and were constructed without uniform federal standards. After that date, all factory-built transportable homes had to meet the HUD Code, and the industry adopted the term "manufactured home" to distinguish these regulated structures from their predecessors.
The HUD Code has been updated over time to reflect modern construction practices. A2024 HUD final rule, which took effect in 2025, updated the code to allow multi-unit manufactured homes (up to four units) under the federal standards—a significant expansion that may help address housing supply shortages. In 2026, the 21st Century ROAD to Housing Act went further, removing the permanent-chassis requirement from the federal definition of a manufactured home.
Manufactured vs. Modular vs. Mobile Homes: What's the Difference?
The terms "manufactured," "modular," and "mobile" often get confused. Here's how they differ:
Feature
Manufactured Home
Modular Home
Mobile Home
Building code
Federal HUD Code
State and local codes
No uniform standard
Build date
After June 15, 1976
Any date
Before June 15, 1976
Construction
100% factory-built on chassis
Factory-built in sections, assembled on-site
Factory-built on chassis
Foundation
Permanent or non-permanent
Permanent
Often non-permanent
Financing
Mortgage or chattel loan
Conventional mortgage
Limited options
Appreciation
Varies by land ownership and upkeep
Similar to site-built
Often depreciates
Modular homes are sometimes confused with manufactured homes because both are factory-built. The difference is that modular homes must meet local building codes—the same codes that apply to site-built homes—and are placed on permanent foundations. Manufactured homes follow the federal HUD Code regardless of where they're installed.
How Can You Buy a Manufactured Home?
Buying a manufactured home follows a similar process to buying any home, but with some key differences in who can buy, where homes can be located, and how financing works.
Who Can Buy a Manufactured Home?
Anyone can purchase a manufactured home, but certain loan programs have eligibility requirements.FHA-backed manufactured home loans, for example, require the home to serve as the borrower's principal residence. FHA financing can cover the home alone even when it sits on a leased lot in a manufactured home community, or the home and land together when the borrower owns the lot in fee simple.
Manufactured homes are particularly popular among first-time buyers, retirees, and anyone looking for lower monthly payments. The entry cost is significantly lower than site-built construction, making homeownership accessible to buyers who might otherwise be priced out.
Where Can You Buy a Manufactured Home?
Manufactured homes can be located in manufactured home communities, on private land in rural areas, or in suburban and urban areas where zoning allows. They are found in communities across the country, and are an especially common choice in rural areas and in states across the South where affordable land is easier to find.
If you don't own land, manufactured home communities (sometimes called "land-lease communities") offer an alternative: you own the home but lease the lot. This lowers your upfront cost but means ongoing monthly lot rent.
Which Lenders Offer Manufactured Home Loans?
Not all lenders offer manufactured home financing, and those that do may have restrictions. Some limit loans to homes on permanent foundations; others won't finance homes older than 15 years. Manufactured home retailers often offer in-house financing, and it pays to compare several lenders to see which offer FHA, VA, USDA, or conventional manufactured home loans.
Credit unions and personal loan providers may finance older or less expensive homes that don't qualify for conventional or government-backed mortgages.
What Does a Manufactured Home Cost?
The cost of a manufactured home depends on size, location, age, and whether you're buying new or used. According to theManufactured Housing Institute, a new manufactured home averages about $123,300 — less than one-third of the $405,939 average for a site-built home. TheU.S. Census Bureau's Manufactured Housing Survey tracks new manufactured-home sale prices month by month if you want to check the most current national and regional figures.
Here's what that looks like broken down (Manufactured Housing Institute):
Home Type
Average Price
Avg. Cost per Sq. Ft.
Single-section manufactured home
$85,200
~$84/sq. ft.
Multi-section manufactured home
$152,000
~$84/sq. ft.
Manufactured home (overall average)
$123,300
~$84/sq. ft.
Site-built home (average)
$405,939
~$169/sq. ft.
These figures reflect the price of the home itself. Delivery, site preparation, utility hookups, and the land (or lot rent in a manufactured home community) are additional costs that vary by location, so budget for them separately.
What Makes Manufactured Homes Less Expensive?
Manufactured homes cost less primarily because of how they're built. Factory construction eliminates weather delays, reduces material waste, and allows for assembly-line efficiency. Bulk purchasing of materials drives down costs further, and the controlled factory environment can improve consistency compared with on-site construction.
Property taxes on manufactured homes are often lower because of their smaller size and assessed value—though this varies by state and whether the home is titled as real property or personal property.
Are Manufactured Homes a Good Investment?
Whether a manufactured home is a good investment depends largely on whether you own the land and how the home is titled — as real property or as personal property (chattel) — along with local market conditions and upkeep. Regardless of how a home is titled, every manufactured home built to the HUD Code must meet the same federal construction and safety standards.
On the cost side, the Manufactured Housing Institute figures above put manufactured homes at roughly half the price per square foot of a site-built home ($84 versus $169). That lower entry point can provide a realistic path to building equity for buyers who can't afford traditional construction.
On the other side, the Federal Housing Finance Agency reports that borrowers financing a manufactured home as personal property (chattel) typically pay higher interest rates than borrowers of site-built homes — averaging 9.24% versus 6.63% — which is worth weighing against the lower purchase price.
Manufactured Home Loans vs. Standard Home Loans
Home Type
Pros
Cons
Manufactured Home
- Alternative financing options including FHA Title I, personal loans, and chattel loans- Lower monthly payments and overall cost- May qualify for government loan programs (FHA, VA, USDA)
- Difficult to secure financing for homes built before June 15, 1976- Fewer eligible lenders and more restrictions on conventional loans- Typically higher interest rates
Standard Home
- Many conventional and government loan options available- Typically lower interest rates- Easier to refinance and typically appreciates over time
- More stringent financing rules make it harder to qualify- Higher monthly payments and down payment requirements
Roughly 70% to 80% of new manufactured homes are titled as personal property and financed with a chattel loan rather than a traditional mortgage, according to theFederal Housing Finance Agency. When a manufactured home is instead titled as real estate and placed on a permanent foundation on land you own, you can typically access conventional mortgage financing with rates closer to those of site-built homes.
How Do You Get a Manufactured Home Loan?
How Can You Find a Manufactured Home Loan?
Start by comparing several lenders that offer manufactured home financing. Many manufactured home retailers also provide financing for the home, the land, or both. You can also check with local credit unions, which sometimes offer competitive rates for manufactured home loans.
If the home doesn't meet the requirements for a conventional mortgage—for example, if it's older or you're renting the land—chattel loans and personal loans are alternatives. These typically have higher rates but shorter terms, so you pay off the debt faster.
How Are Manufactured Home Loans Different From Standard Home Loans?
Conventional manufactured home loans function like traditional mortgages when the home meets certain criteria: it must be titled as real property, affixed to a permanent foundation, and built after June 15, 1976 with a HUD certification label. Rates are typically slightly higher than for site-built homes.
Chattel loans are designed for buyers who own the home but rent the land. These loans treat the home as personal property (like a car) rather than real estate. Rates are higher, but terms are shorter—often 15–20 years instead of 30. Personal loans offer another option for financing older or lower-cost homes that don't qualify for other programs.
What Documents Do You Need for a Manufactured Home Loan?
Before you apply, gather:
Credit reports (check for errors and dispute any mistakes)
The listing sheet and title to the home
Title to the land or a park lease agreement if renting the lot
Proof of income and recent tax returns
Homeowners insurance documentation
Documentation of funds for the down payment
Having these documents ready speeds up the application process and helps you get accurate rate quotes.
Who Is This Guide For?
This guide may be especially helpful if you're:
A first-time homebuyer on a budget — Manufactured homes offer lower entry costs and monthly payments than site-built homes. If that's you, ourfirst-time home buyer checklist walks through each step.
A buyer who owns rural land — If you already have a lot, a manufactured home can provide an affordable way to build on it.
Comparing manufactured vs. modular homes — Understanding the building code, financing, and appreciation differences can guide your decision.
A buyer who doesn't own land — Chattel loans and land-lease communities offer paths to homeownership without buying property.
Looking to downsize or retire affordably — Manufactured homes offer practical, customizable living at a fraction of traditional home costs.
What Should You Do Next?
If a manufactured home sounds like it might fit your goals, here are practical next steps:
Compare lenders: Look at several lenders that offer manufactured home loans and see what rates and terms you may qualify for.
Check your credit: Review your credit reports before applying. Dispute any errors that could lower your score.
Calculate your budget: Factor in the home price, delivery and setup costs, land or lot rent, and closing costs. Read our guide tohow your debt-to-income ratio affects your mortgage to understand how lenders evaluate your application.
Decide on land: Will you buy land, rent in a community, or place the home on property you already own? This choice determines your financing options.
Your Questions, Answered (FAQs)
What is the difference between a manufactured home and a mobile home?
The terms refer to when the home was built. A manufactured home was built after June 15, 1976, under federal HUD Code standards. A mobile home was built before that date, without uniform federal construction standards. The HUD Code established safety, construction, and energy requirements that all manufactured homes must meet.
How much does a manufactured home cost in 2026?
According to the Manufactured Housing Institute, a new manufactured home averages about $123,300 — single-section homes average around $85,200 and multi-section homes around $152,000. That's less than one-third the $405,939 average for a site-built home. Delivery, installation, and land are additional costs.
Can you get a mortgage on a manufactured home?
Yes, if the home is titled as real property, placed on a permanent foundation, and built after June 15, 1976 with a HUD certification label. FHA, VA, USDA, and conventional manufactured home mortgages are available. If you rent the land or the home doesn't meet these criteria, a chattel loan or personal loan may be an option instead.
Do manufactured homes go up in value?
It depends. Whether a manufactured home holds its value comes down largely to whether you own the land, how the home is titled (real property versus personal property), local market conditions, and how well the home is maintained. Newer, well-kept homes on land you own generally hold value better than older homes on leased lots.
Why Trust BestMoney?
About the author: Patrick Sather is a personal finance writer covering mortgages, home buying, and homeownership topics. His work focuses on helping readers understand their financing options and make informed decisions.
At BestMoney, we help you compare your options with confidence. We review and compare financial products based on multiple factors, including costs, features, eligibility requirements, and reader needs. Our editorial team evaluates providers to help you make informed decisions—we're not a neutral party, but we are committed to clear, well-researched information.
Our Research
This article draws on cost data from the Manufactured Housing Institute and the U.S. Census Bureau's Manufactured Housing Survey, which tracks pricing, shipments, and characteristics of manufactured homes (both linked above). We also referenced construction and safety standards from the HUD Office of Manufactured Housing Programs.
For the 2026 change to the federal definition of a manufactured home, we reviewed a section-by-section summary of the 21st Century ROAD to Housing Act (linked above) and HUD's manufactured-home construction rulemaking in the Federal Register (linked above). Financing and titling data reflect Federal Housing Finance Agency reporting on manufactured-home loans.
Where We Got Our Information
Manufactured Housing Institute, "About Manufactured Homes" (cost data cited inline above)
U.S. Census Bureau, Manufactured Housing Survey (MHS) — census.gov/programs-surveys/mhs (linked above)
HUD Office of Manufactured Housing Programs (HUD Code and homeowner resources; cited inline above)
Bipartisan Policy Center, "Inside the Deal: What's in the Final 21st Century ROAD to Housing Act" (2026 chassis definition change; cited inline above)
Federal Register, HUD "Manufactured Home Construction and Safety Standards" final rule (2025 multi-unit update; cited inline above)
Federal Housing Finance Agency — manufactured-home loan and titling data
Written byPatrick Sather
Patrick Sather is a personal finance expert at BestMoney.com, specializing in online banking. He is an award-winning writer and licensed broker who has worked at leading financial firms such as TD Ameritrade and Pacific Life. With degrees in Economics, International Trade, and English from the University of Nebraska, Patrick delivers practical advice on financial decisions.